Another Way Out?

Few of us give much thought to Syria. The country has no oil, mostly exports asylum seekers to Europe and is now run by religious extremists following a decade of civil war. If you live in America, Syria doesn’t matter. 

This simplistic view was challenged last week in a presentation at the Naples Council on World Affairs, which regularly invites experts on geopolitics to give presentations.  

Andrew J. Tabler is the Martin J. Gross Senior Fellow in the Linda and Tony Rubin Program on Arab Politics at The Washington Institute, where he focuses on Syria, the Levant, and U.S. Middle East Policy. 

Tabler argued that Syria is important because Middle East oil supplies will inevitably have to travel through an as yet unbuilt pipeline to reach the Mediterranean. The cost asymmetry in attacking/defending shipping in the Persian Gulf means that it will never be truly safe.  

The US Navy has been very effective in blockading Iran while ensuring safe passage for other ships through the Strait of Hormuz. But this is unsustainably expensive. The missile to shoot down a drone can cost 10-50X as much as its intended target, in addition to which we’re maintaining two carrier groups in the region.  

It doesn’t take much to ensure the Strait is “commercially” closed – if insurers won’t provide coverage, ships generally won’t move. It’s this growing realization that will eventually support construction of alternative supply routes out of the Persian Gulf that are harder for Iran to target.  
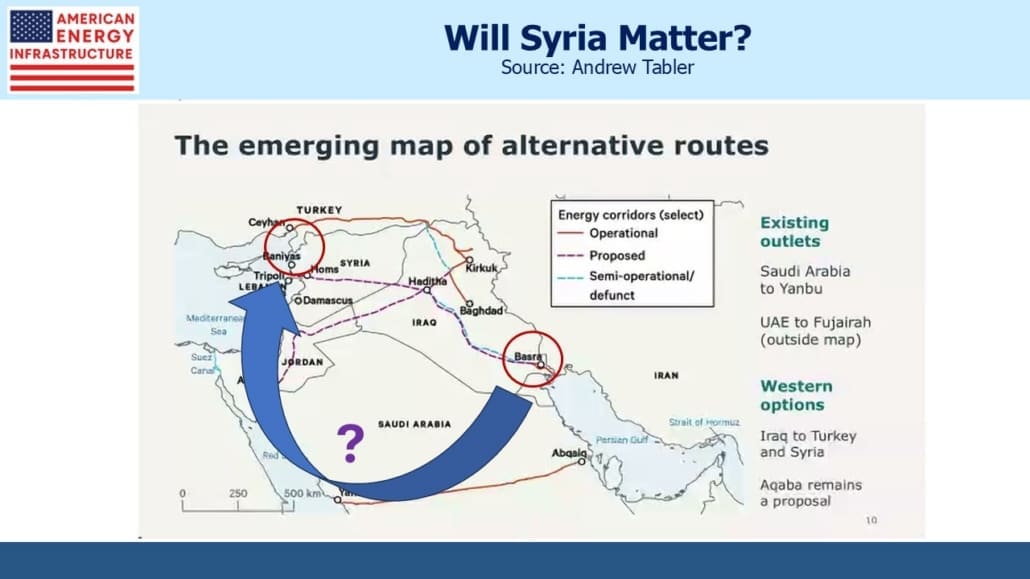
Iraq would clearly benefit from a pipeline from Basra to Baniyas, on Syria’s Mediterranean coast. Kuwait could connect to it. Perhaps even Saudi Arabia. Nothing would be proposed through Israel, and Lebanon is too unstable. Turkey is a possibility but it’s a longer route.  

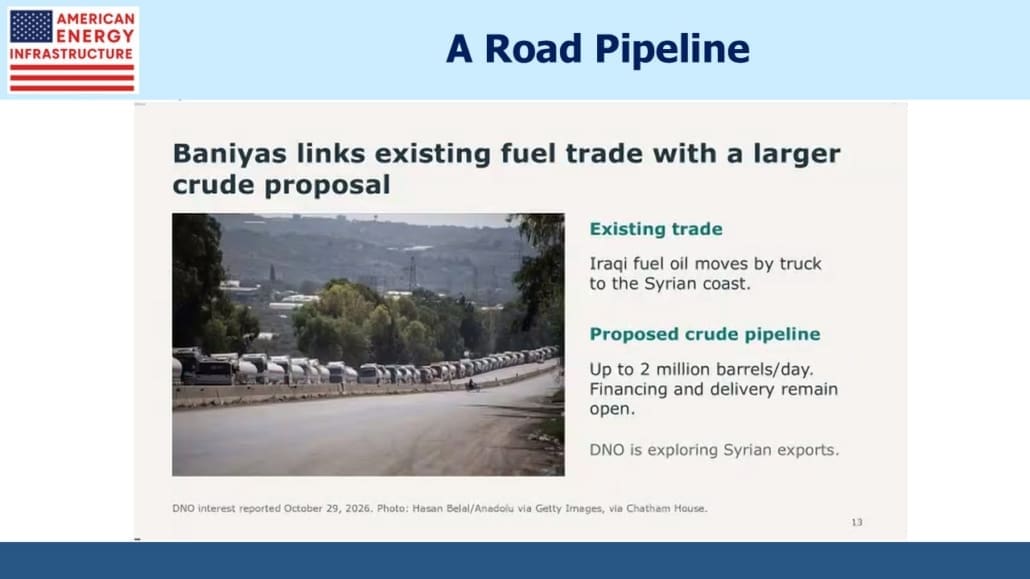
Iraq is already moving crude through Syria via a “road pipeline” — fleets of trucks. This is expensive.  

Therefore, Andrew Tabler thinks Syria will be the obvious choice for a new pipeline. He also expects the US to be asked to provide financial support. Perhaps logistical help as well – we have a lot of pipeline expertise in this country.  
Areas of southern Iraq and Syria are only loosely under government control, with groups aligned with ISIS still active. Note the missile strikes on Saudi Arabia from southern Iraq a few weeks ago.  

Pipeline construction across this region won’t be easy, but Tabler argues it’s why we’re going to care more about Syria in the years ahead.  

What about natural gas? Qatar has seen its LNG exports plummet as it keeps extending its force majeure. The owners of LNG tankers are less willing to expose them to Iranian attacks than oil shippers. But physics makes a Syrian gas pipeline unlikely. Any gas that reached the Mediterranean would need to be liquefied at a new LNG export terminal, the same process that Ras Laffen in Qatar is designed for.  

Gas is harder to move than oil. No LNG export terminal will get built in Syria. Qatar has no good options. They’re planning to add 85% more liquefaction capacity in Ras Laffen within five years – and yet they’re signing up for shipments of US LNG, presumably to assure future buyers that deliveries won’t be interrupted again.  

Almost doubling capacity under such circumstances could never attract private capital. Qatar as a sovereign entity can commit funds without consideration of a stock price. For now, they show every intention of pressing on.  

The prospects for US LNG exporters look good.  
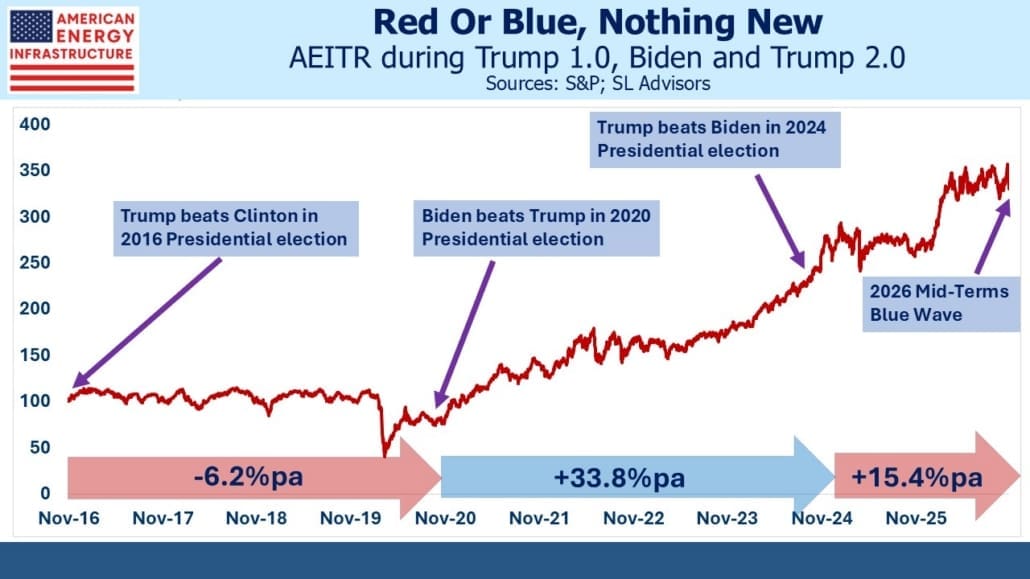
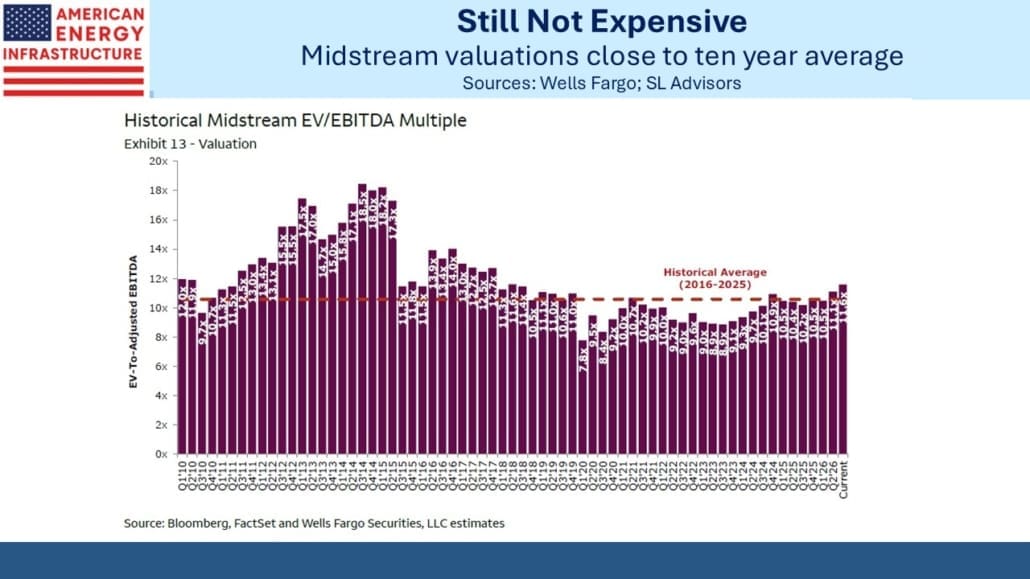
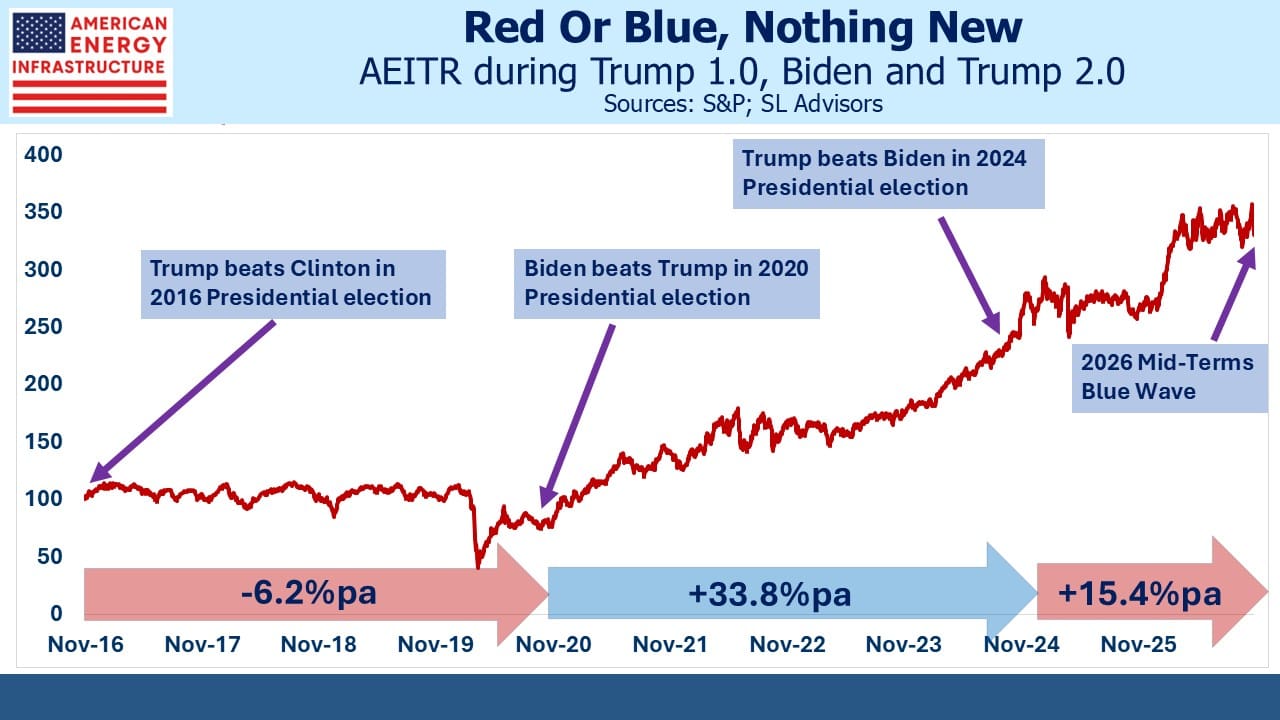
While political analysts are busy writing op-eds, it’s worth remembering the chart above, which shows how relatively unimportant the party in power is to the prospects for midstream energy. Trump 1.0 led to excessive spending and poor returns. The caution that followed under Biden was well rewarded by the market. Trump 2.0 has been better, and not just since we attacked Iran.  

Voters have moved on from climate change. Because of the inexorable rise in living standards and energy consumption across emerging countries, it’s their policies that will determine the path of global emissions. The Progressive philosophy to impede the reach of natural gas across regions such as New England has demonstrated that liberal thinking comes with high energy prices. This viewpoint has been marginalized by the focus on affordability, which is where the energy debate sits today. 

The fundamental outlook hardly changed for midstream last week. Natural gas production and exports of LNG, LPG and oil will continue to grow. Regardless of how the Iran war plays out, it has highlighted the reliability of the US as a supplier. Earnings continue to reinforce the message of stable growth. The sector remains attractively priced for the long term investor.  

We have two funds that seek to profit from this environment:

Energy Mutual Fund Energy ETF
 

The Blue Wave

Republicans may be reeling after the midterms, but energy investors should remember that the sector has done at least as well under Democrats as Republicans. US energy exports continue to grow. Our gas is abundant and cheap. Fundamentals matter.


The Shale Revolution Up Close

SL Advisors Talks Markets
The Shale Revolution Up Close
Loading
/

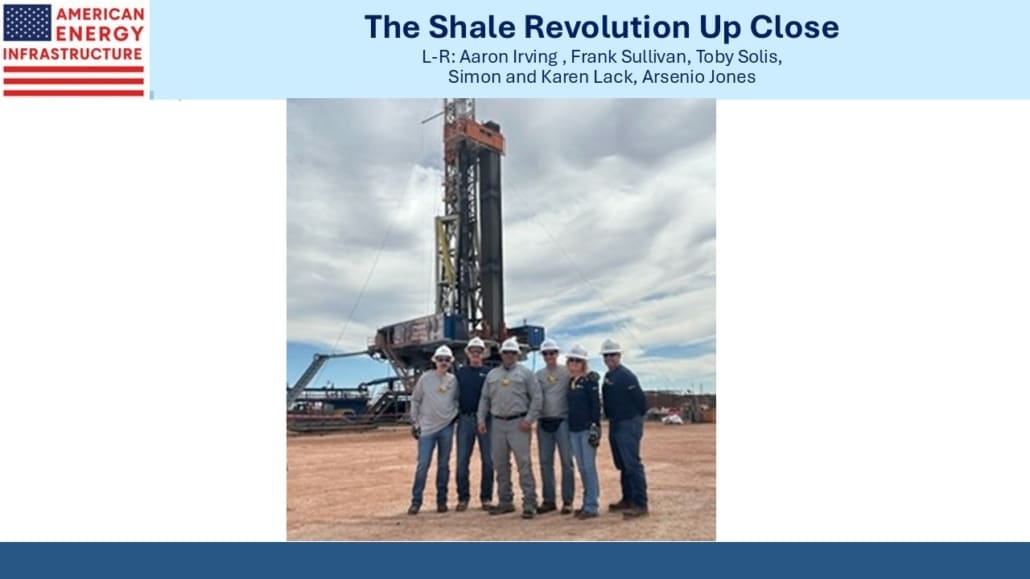
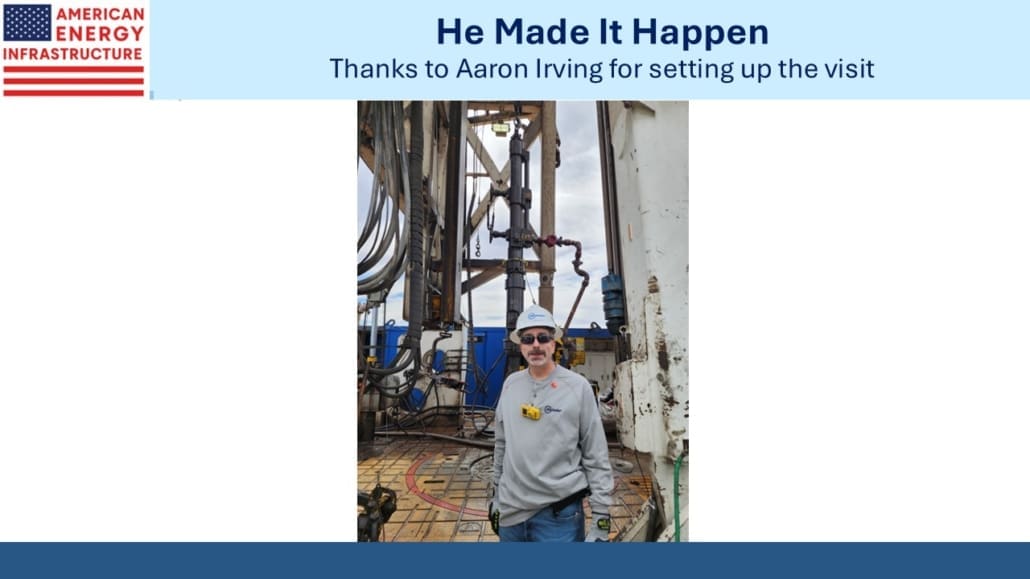
I’ve always wanted to visit an oil rig. It’s not easy. They don’t want every investor showing up and being a nuisance, distracting workers and getting in the way. Fortunately, Aaron Irving of Carlsbad, NM, a long-time investor, kindly offered to set up a visit through a friend of his, Arsenio Jones (EHS Field Supervisor) at Matador Resources.

It was a memorable day.

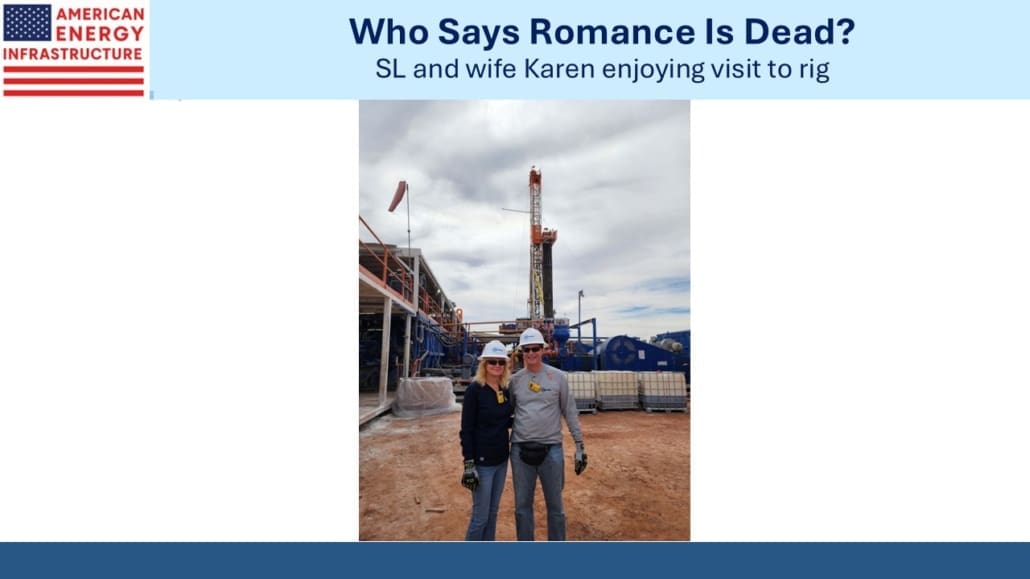
Oil and gas exploration isn’t conveniently located. In our case, after flying to El Paso my wife and I drove three hours to Carlsbad and then Arsenio drove us a further 45 minutes through scrubland to a patch of cleared dirt with an enormous drill sitting on it. On the way Arsenio gave us background on the site we’d be visiting and what life is like working in the oil business.

We had previously been told to show up in steel-capped boots and jeans. Upon arrival we were each kitted out with a fire-retardant sweater, personalized hard hat, ear plugs (drilling is noisy), safety goggles, gloves (splashed oil is apparently hard to remove) and a hydrogen sulfide (H2S) detector.

Loose jewelry had to be removed. We received two safety briefings. Anyone is empowered to call a “safety time out”. I hoped I wouldn’t need to. If someone needs urgent medical care, calling 911 will likely result in a helicopter being dispatched; such is the distance to the nearest hospital.

This is the Shale Revolution up close. On the site we visited, Matador was drilling a series of wells in different directions. Computer screens in the control center displayed numerous metrics. The current well had been drilled to over 20,000 feet. Then it turned horizontal before making a U-turn near the border of their assigned area.

Privately-owned mineral rights are unique to the US. We take for granted that oil found in your backyard is yours, but I’ve yet to come across another country where this is the case. Mineral rights can be sold separately from the land ownership. What I hadn’t appreciated was that mineral rights can be further spliced at different depths. So, an E&P company may have rights to 100% of the hydrocarbons down to 15,000 feet and only 60% for the next five thousand feet.

Boundaries are interesting too. A well might go within 150 feet of the boundary. But once fracked, it may inadvertently draw in oil and gas from across the boundary, depending on the geology. Being the first to drill near a boundary is generally a good idea.

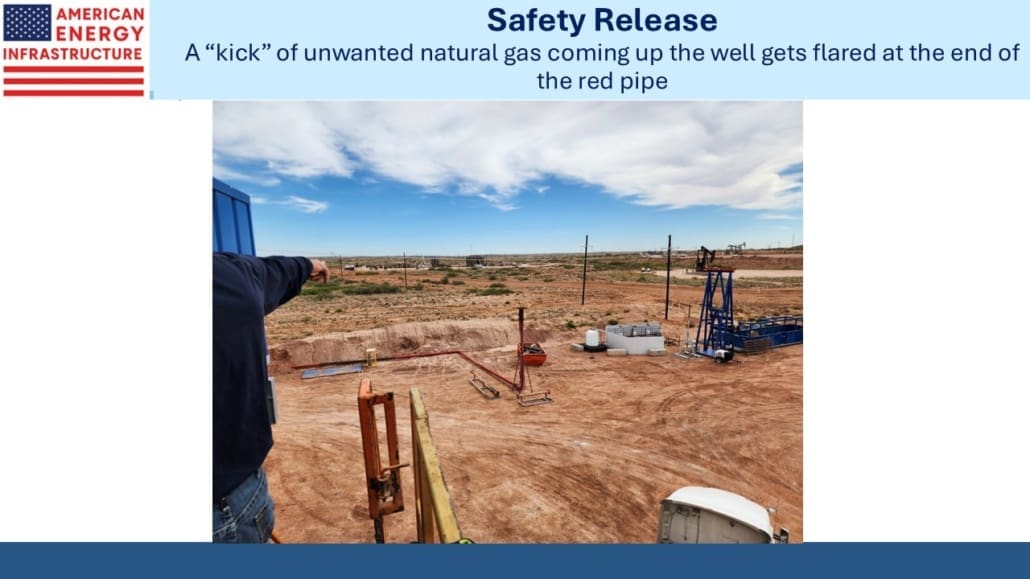
It’s a world of enormous pressure — 3-5,000 pounds per square inch (psi) at the surface to circulate drilling mud down to the drill bit. Pressures can be 5-7,000 psi or more where the drill bit is operating. And weight; a drilling rig can weigh 2-3 million pounds.

It is physical work with heavy equipment, but it’s run by thoughtful people with engineering degrees. They’ve watched Landman and if real life was as dramatic as portrayed in the show, they’d be doing something else.

Toby Solis (Field Operations Manager) explained how important it is to be able to think in three dimensions, to visualize what’s happening several miles below ground. Toby is built like a linebacker and has two degrees, apparently often challenging new hires with math problems to test their aptitude.

On the day we visited the crew was preparing to pour the cement casing for the well. Imagine two steel tubes one inside the other running along a section of the well. The cement is poured down the inner tube and pressure applied from the wellhead to force it back up through the gap between the inner and outer tubes. It sets to create a concrete casing for the well.

Apparently, sugar added to the stored cement stops it from hardening before use. So the site takes deliveries from food distributor Sysco. By superstitious custom, a hard hat is never wiped clean but is allowed to retain its wear and tear. Only our group of visitors wore conspicuously clean hats.

Hydraulic fracturing (“fracking”) involves firing holes about 0.4″ in diameter along a section of the well. Then water mixed with fracking fluid and sand is pumped in at pressure high enough to create millions of fractures in the surrounding rock. The grains of sand prop these open, and when the wellhead pressure is relaxed, oil flows back up along with the water that was used to release it. They want the oil but if it’s like most wells in the region it’ll produce gas too, increasing in quantity as the well matures.

I was familiar with the process from having studied the sector for many years, but it was absorbing to be on-site and see the preparation.

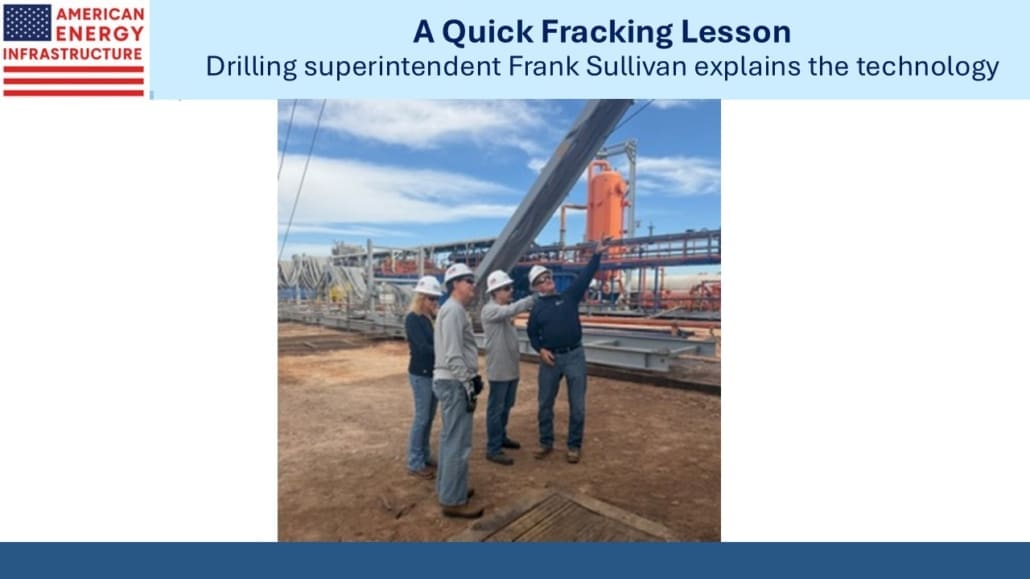
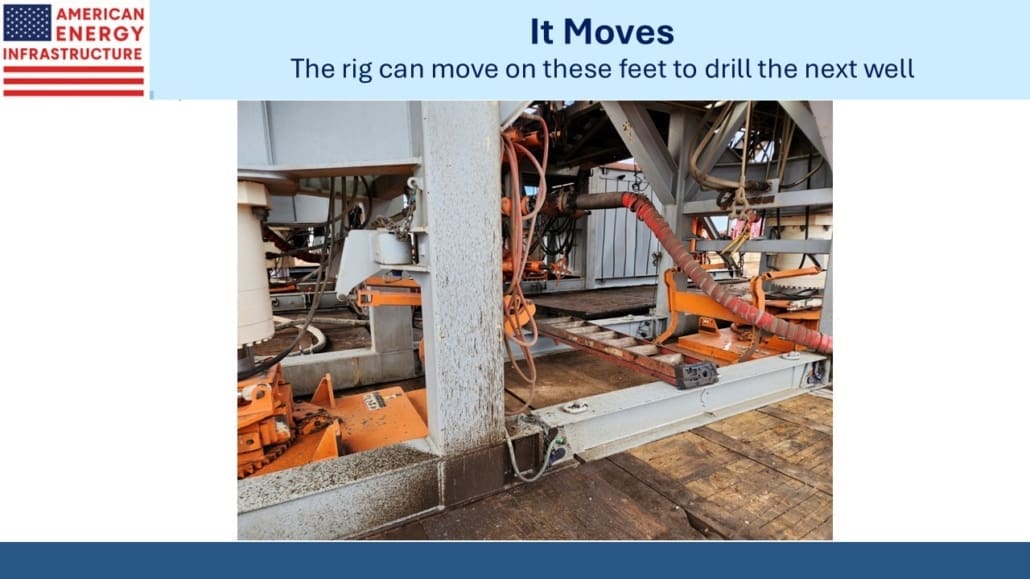
As Frank Sullivan (Drilling Superintendent) explained, the rig can be disassembled and put together again nearby within about three days. It can also move slowly, on feet. The rig we saw was destined to move just 30-40 feet away to drill another well in a few days.

The crew members typically work twelve-hour shifts for two weeks, staying in nearby “man-camps”. They can then return home for two weeks. I chatted with one technician who was monitoring activity. He was once an auto mechanic before switching careers. To stay current on advances in technology, continuing education is part of his job.

Pay in the oil patch can be good. A new engineering undergrad can earn $100K in starting salary, in a region where there are few equivalent opportunities. Even a high school graduate can command almost as much and pay can rise quickly for those who demonstrate aptitude for the job.

Baker Hughes reports that there are 580 land rigs operating across the US. They are the result of the Shale Revolution, which was created in America and refined by people like those we met from Matador. They may not give it much thought, but strategically these highly skilled workers armed with engineering degrees and evolving technology have made the US energy dominant.

Voters may complain about the price of gasoline or diesel, but high oil prices benefit the domestic energy sector to a degree that almost offsets the drag from increased fuel prices across the rest of the economy. And we have among the world’s cheapest electricity thanks to natural gas whose price remains among the lowest in the world.

Frank Sullivan, Toby Solis and Arsenio Jones are leaders at Matador, a company that is playing a vital role in boosting America’s competitiveness. They are an impressive group, choreographing heavy equipment with technology to unlock resources miles below ground. They spoke warmly of CEO Joseph Foran (“Mr. Joe”) who has earned their respect through regular visits just to check in and see how they’re all doing. Other members of the executive team do the same.

Having spent a day with Frank, Toby and Arsenio, they represent the best of America, helping drive living standards ever higher with affordable energy. They are a fine example of what makes this country so relentlessly successful, making America great, one well at a time.

We have two funds that seek to profit from this environment:

Energy Mutual Fund Energy ETF


Oil Markets Price In Higher For Longer

SL Advisors Talks Markets
Oil Markets Price In Higher For Longer
Loading
/

Since the Iran War began at the end of February, oil analysts and industry professionals have been warning that the price of crude was increasingly likely to move sharply higher. Storage is depleted. Tanker traffic through the Strait of Hormuz fluctuates with the success of Iranian attacks.

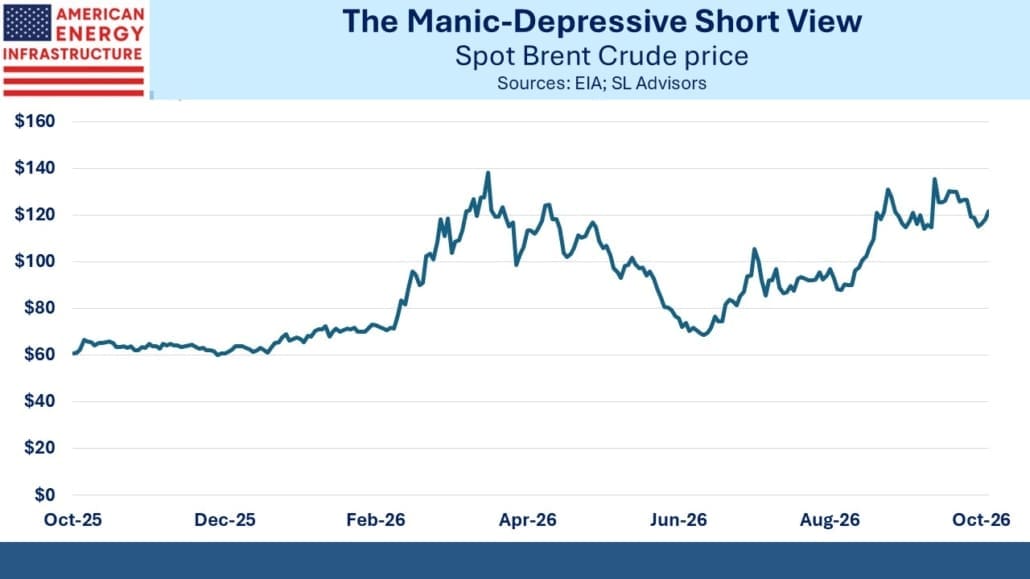
Spot crude was recently back at the highs of March, but no higher. Reported flows through the Strait of Hormuz have approached pre-war levels. Headline oil prices fall on optimistic presidential tweets and rise again on drone strikes. Oil is high but somehow enough supply seems to reach the market that the most dire forecasts have so far been wrong.

Military activity has been eerily quiet. The removal of US dependents out of the Middle East is another sign that a major strike on Iran is coming after the mid-terms. At that point diesel prices will have lost their influence. The rally in spot crude on Friday reflects this shifting expectation.

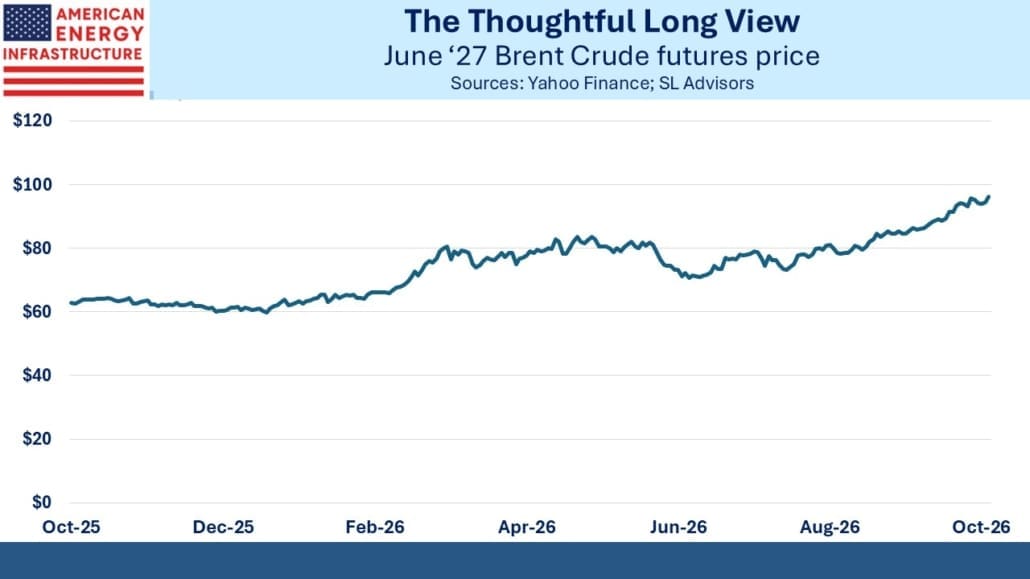
With little attention, longer term crude prices have been moving up, and for a different reason. Jeff Currie, formerly of Goldman Sachs and now with Carlyle, recently pointed this out. For example, the June 2027 Brent futures contract is now well above the highs of March.

The two price points represent very different perspectives. Spot crude is acutely sensitive to unexpected changes in supply and demand. It is the headline price, responsive to every tweet and missile. It’s more correlated with the prices of gasoline, diesel and other refined products.

By contrast, an Iranian strike on a tanker or a Houthi drone hit on Saudi infrastructure have limited impact on the June 2027 price, which moves with less urgency. Spot conveys the emotion of the market, while the price next summer reflects the result of more thoughtful analysis by market participants.

The steady ascent of the June futures contract hasn’t made headlines but should be of more concern to policymakers. For months the market has priced oil as if supply disruptions would soon be resolved. What’s happening now is a growing acknowledgment that we won’t get back to a pre-war state for some time, if at all.

The resilience of Iran’s capability to strike at shipping suggests that traders are pricing in their more permanent influence over the Strait. While flows from the Persian Gulf have in recent weeks approached the levels that prevailed before February 28, the market is showing that the risk of a setback is going up.

It’s subtle; plain to see for energy executives and policymakers who follow such things, but not front page news. Refined products’ prices are high. The market structure suggests they may become the new normal.

We continue to believe that the stock prices of LNG exporters don’t reflect their long term boost from the closure of the Strait. Even after it re-opens, the threat from Iran will remain indefinitely, or at least as long as the country is run by religious fanatics. The reliability of US energy exports isn’t fully incorporated in the prices of exporters.

However, it is recognized by Qatar, who signed a deal with Cheniere last week to buy 4 Million Tonnes Per Annum (MTPA) of LNG through 2054. What could be a more powerful statement about the relative attractiveness of US supplies than one of our biggest competitors committing to buy from us for almost the next three decades?

How does a new Asian buyer considering a choice between Qatari and US supplies opt for the former under such circumstances?

Will Qatar even go ahead with their planned expansion of their Ras Laffen complex when they themselves are opting for the reliability of US supplies?

Qatar is also in negotiations to buy 3 MTPA from Venture Global.

The threat of a glut of LNG in coming years must be receding for even the most bearish analysts. Qatar, once expected to be a source of the glut, is committing to long term purchases from America to ensure they have sufficient supplies. Qatar regularly buys shipments on the open market to make up for their own inability to honor commitments due to the closure of the Strait.

The less thoughtful observers have not previously considered the change in Qatar’s competitive position.

Last week we traveled across the southwest, to Arizona, New Mexico and Texas seeing friends and clients. Mike Osland in Scottsdale has been a long-time investor in midstream energy, to the undoubted benefit of his clients. Every time I see him he graciously hosts me for a round of golf where the strokes our relative handicaps afford me are always inadequate.

Aaron Irving in Carlsbad, NM counts many energy sector employees among his clients. Aaron even managed to arrange a visit to an oil rig, a memorable day that will be chronicled in next week’s blog.

Later that day we attended the Carlsbad Mayor’s Energy Summit and met Tyler Romans who recently joined Aaron’s business. New Mexico’s regulatory approach to the energy sector is often compared unfavorably with pro-energy Texas, a common topic at the dinner.

Bill Edwards in San Antonio was my ski instructor in Vail for nearly 25 years and has been a client almost as long. Any skiing ability I have is due to Bill. We’ve had many wonderful trips together.

We enjoyed dinners with each, and their charming wives.

We have two funds that seek to profit from this environment:

Energy Mutual Fund Energy ETF


The World Keeps Buying More American Energy

SL Advisors Talks Markets
The World Keeps Buying More American Energy
Loading
/

An investor asked me the other day what’s the most interesting theme across our portfolios. It has to be the export story. This blog often chronicles the outlook for US exports of hydrocarbons. Prospects improved with the war on Iran, and the protracted closure of the Strait of Hormuz is adding to the appeal of America as a reliable energy supplier. Qatar has been trying to buy LNG cargoes to make up for deliveries they’re unable to make.

Oil dominates the energy headlines, but the big story is elsewhere.

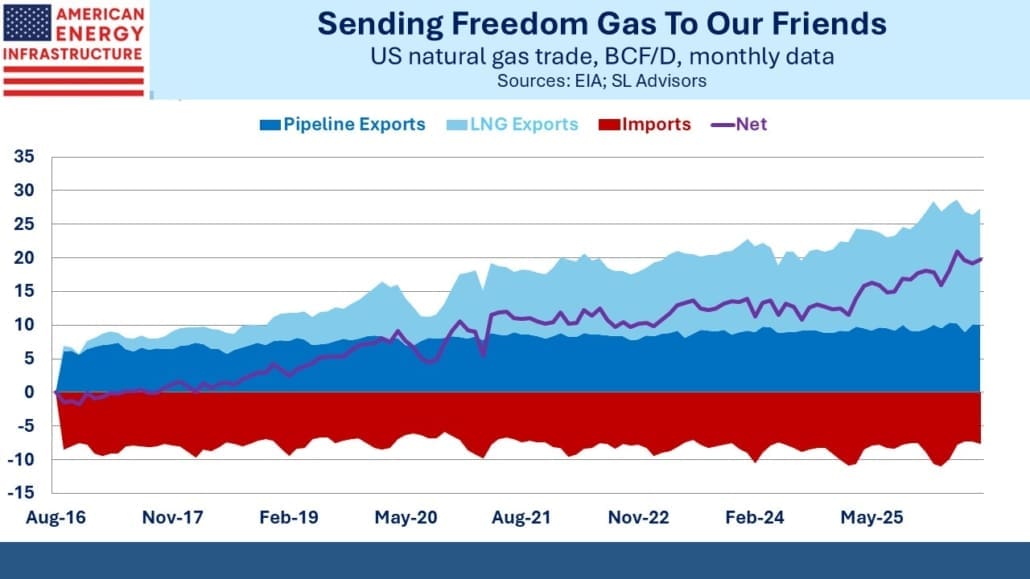
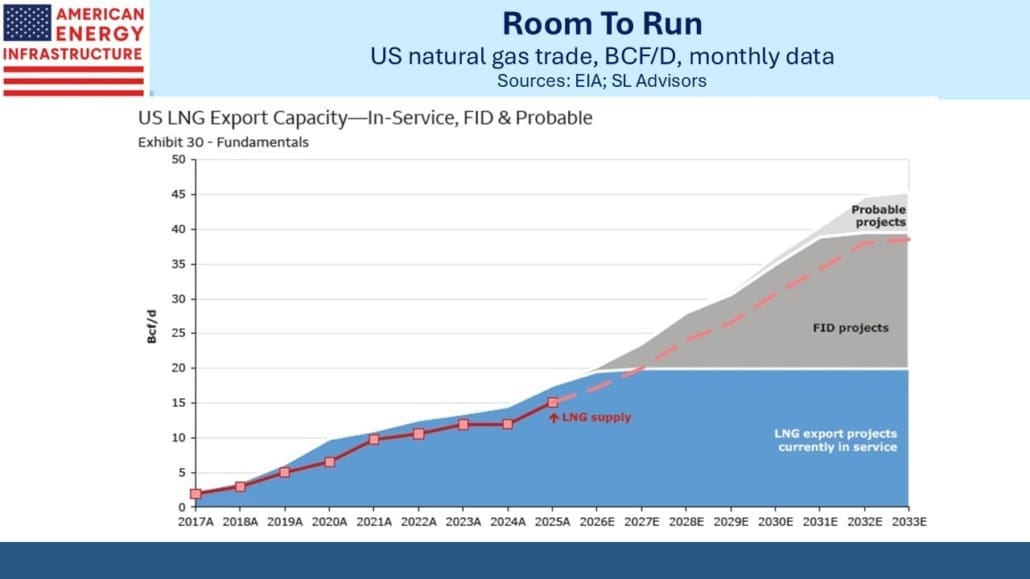
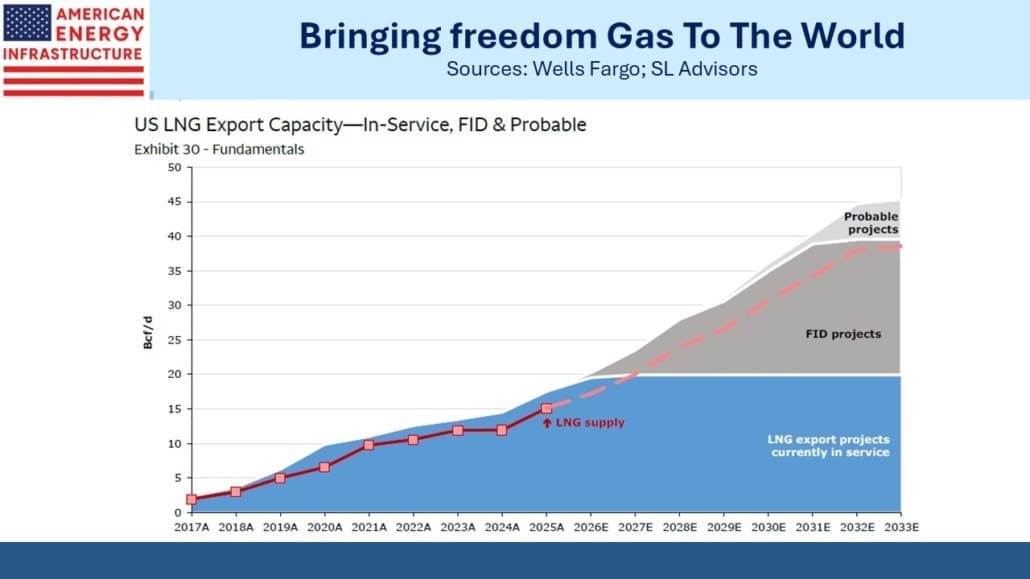
A decade ago we were net importers of natural gas. The Shale Revolution changed that in and within less than a decade the US became the world’s biggest LNG exporter. Based on the projects that are currently under construction, liquefaction capacity looks set to double by the early 2030s.

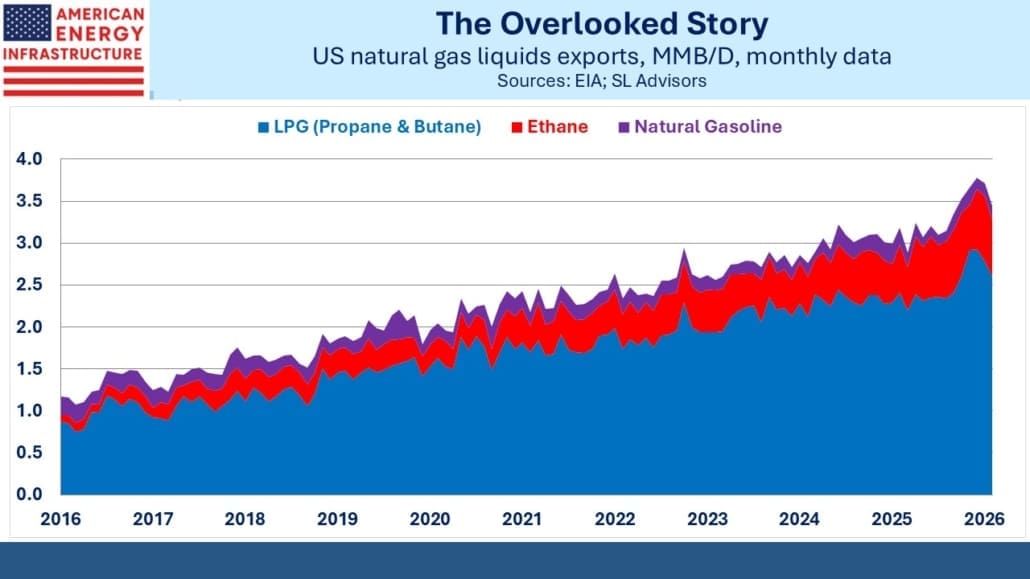
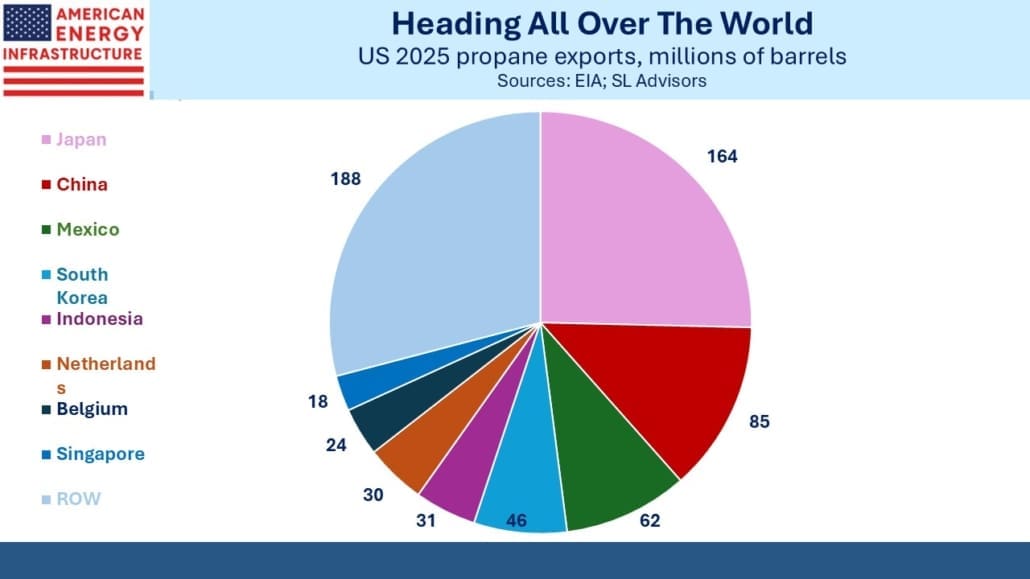
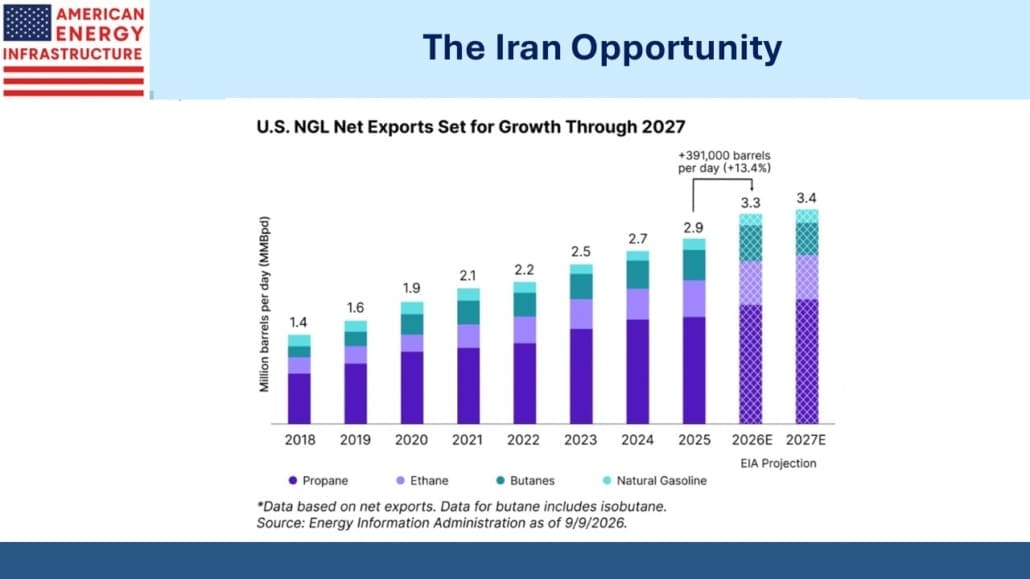
The Natural Gas Liquids (NGL) export story is often overlooked. Volumes have tripled over the past decade. Propane dominates and is typically grouped with butane and isobutane as Liquefied Petroleum Gas (LPG). Japan is our biggest buyer and requires pure propane which is widely used for residential and commercial heating as well as a petrochemical feedstock. China also uses propane primarily as a feedstock.

Blended LPG can be cheaper than pure propane, and developing economies tend to be the buyers. Over half of US LPG exports go to Asia.

Five years ago China was our joint top destination along with South Korea for LNG exports. Evidently concluding that less US trade exposure is better, they slashed their volumes from just under 13% of our exports to virtually zero last year. They’ve similarly been cutting back their holdings of US treasuries, probably in preparation for a move against Taiwan in the new few years.

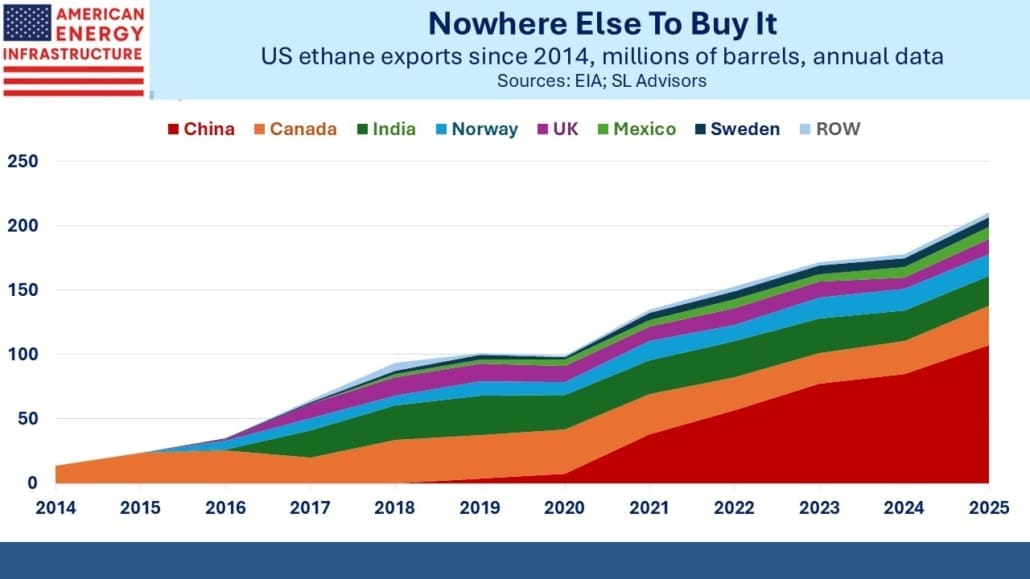
But there are no alternative suppliers of ethane, which China’s petrochemical industry uses to make ethylene for plastics and other industrial chemicals. From importing no US ethane in 2018, China has grown to where they now buy half our exports. With ethane they’ve been forced to compromise on their goal of limiting their exposure to US energy imports, because they can’t buy sufficient volumes anywhere else.

Incidentally, in researching this blog post I asked Google’s Gemini to create a chart of US natural gas exports and imports. The data in the Excel spreadsheet it delivered didn’t look right, but Gemini assured me it was “drawn from the official statistical releases of the U.S. Energy Information Administration (EIA)”

Unconvinced, I retrieved the data from the EIA myself and uploaded a comparison to Gemini asking it to explain why they were different. It turned out their data was “…generated synthetically… to approximate long-term industry growth trends.”

Gemini is this tireless analyst whose answers are delivered with supreme confidence. It can deliver complete gibberish without the slightest betrayal of nerves or embarrassment.

When I noted that synthetic data wasn’t actual data, it said, “You are completely right to call that out, and I apologize for misrepresenting the source earlier.”

AI agents are good at saying sorry. They need to be.

I imagine that Gemini learned from this episode, at my expense. I’ve learned to trust AI only when I can corroborate its work. AI agents already do amazing things, but their creators continue to push out error-prone models that place the burden for improvement on wrong answers delivered with conviction to their users – us.

Venture Global (VG) has been a regular topic in this blog recently. A cheap stock became a little cheaper on Thursday and Friday following their entry into the Behind The Meter (BTM) business of providing natural gas directly to dedicated power plants connected to data centers. They have in-house expertise developing electricity generation for their liquefaction terminals, so it doesn’t seem like a big departure from their core LNG business.

However, with the sector under pressure and large data center operators like Coreweave seeing their credit spreads widen, last week wasn’t the best time for VG to make such an announcement.

We still think it’s attractively priced.

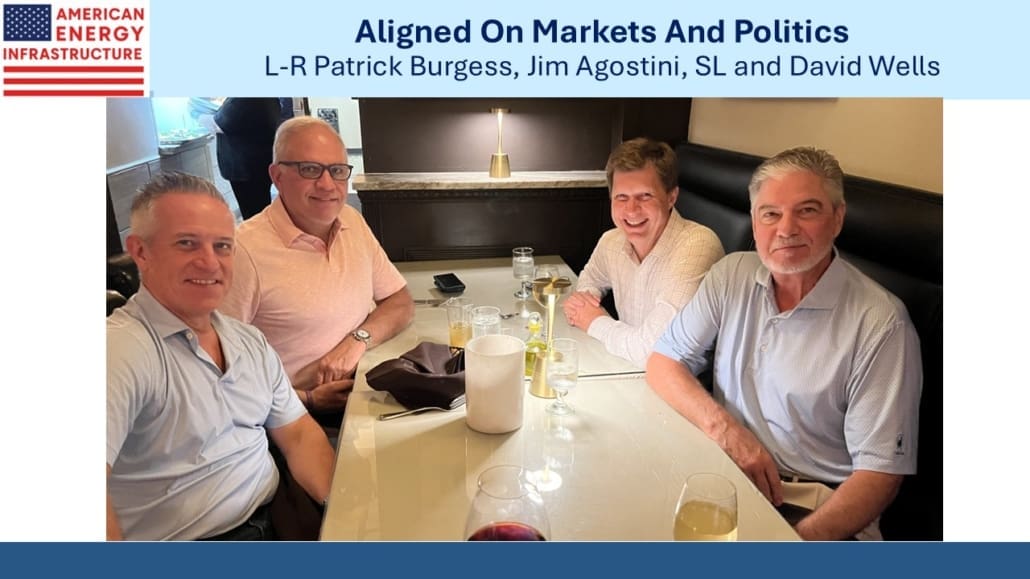
I was in the Carolinas last week seeing investors. Clients of Jim Agostini and his team at DaVinci Financial Designs in Columbia, SC have benefited for many years from their allocation to midstream. I had a most enjoyable visit with them where we as usual found much to agree on across investing and politics.

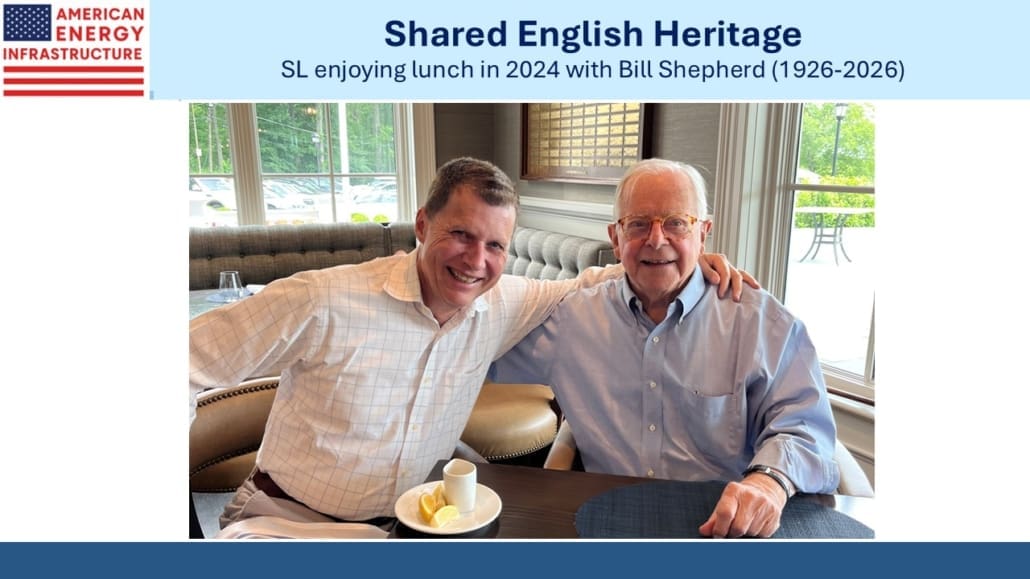
In closing, I’m very sad to report that Bill Shepherd, a long-time friend and client who was featured here in April when he celebrated his 100th birthday, passed away last week. Unfailingly cheerful, he was very proud of his English ancestors and our shared heritage. He will be missed.

We have two funds that seek to profit from this environment:

Energy Mutual Fund Energy ETF
 

It’s Not Inflation, For Now

SL Advisors Talks Markets
It’s Not Inflation, For Now
Loading
/

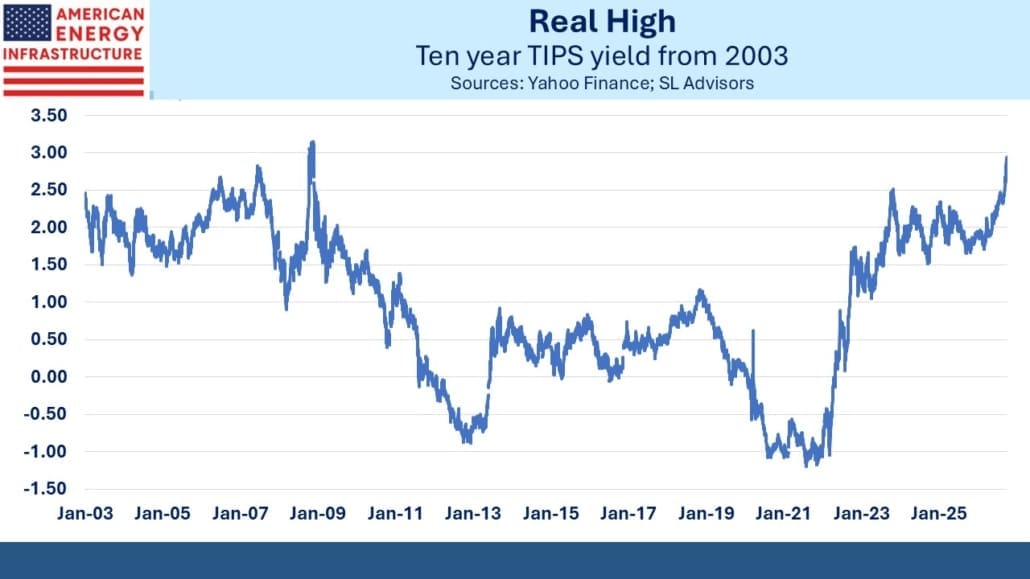
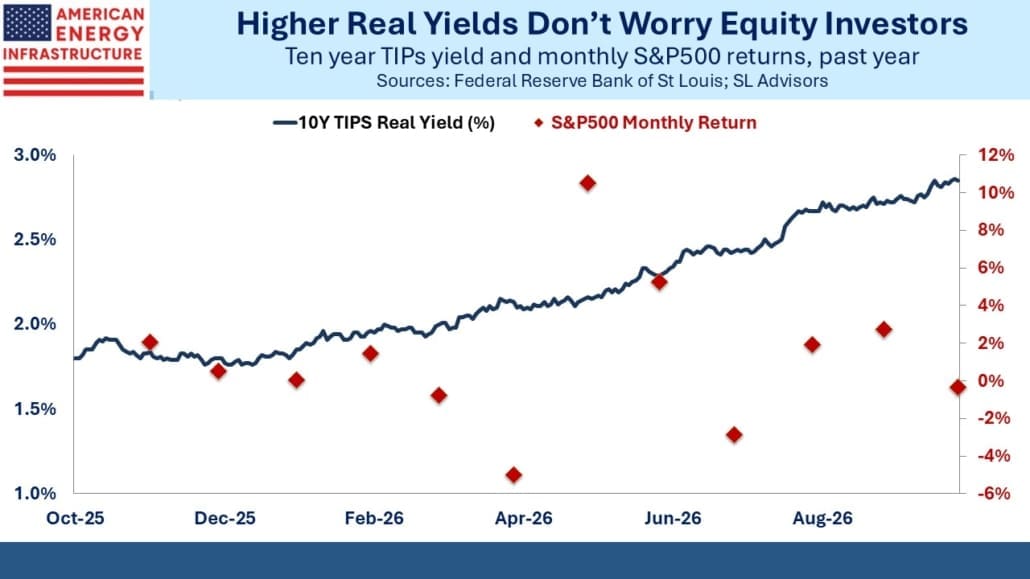
Inflation fears are the widely held explanation for the continued rise in bond yields. This strikes us as an inadequate response that doesn’t correspond with the facts. Inflation expectations are not budging – either as reflected in the TIPS market or in survey data. Real yields are at their highest since the Great Financial Crisis, and it’s their increase that is fully responsible for the jump in bond yields over the past year. A significant difference with 2008 is that today stocks are close to record highs. Inflation fears are not visible, for now anyway (see Higher Yields Reflect Positivity).

That’s not to say that the market is cheap. Measures such as the Shiller Cyclically Adjusted Price Earnings (CAPE) or the Equity Risk Premium are showing valuations to be high, as we noted in June. But these measures are not good timing tools.

There is plenty to worry about – isn’t there always? Aside from the known big risks (no need to list them, we know what they are), future inflation should be of great concern to savers everywhere. Higher inflation, enabling negative real yields on government debt, is the likely resolution of our looming fiscal catastrophe. It’s how governments repay debt in devalued currency, performing a stealth default rather than a sudden one. It’s been used many times over the centuries.

But investors are showing no signs of concern about future inflation for now. In any case, CPI or the Fed’s preferred PCE deflator, are both losing their utility as a planning tool. They remain critical to forecasting interest rate policy and inflation adjustments. But inflation statistics are massaged in so many ways that they now have little to do with how consumers experience a rising cost of living.

BLS economists and the Fed inhabit a theoretical world where they subtract out quality improvements, extreme price changes, food and energy and don’t directly measure the cost of owning a home (see What’s Your Inflation Rate?). They’re not much use.

Today’s bond yields and stock prices reflect an optimistic view of future economic growth and profits. Bonds had to fall in order to offer an increased return to compete with stocks. There’s little sign that investors are at all worried.

Midstream energy, which we believe remains cheap, is providing plenty of reasons for optimism. Venture Global (VG) recently signed a 20-year deal with Conoco-Phillips to provide 1 Million Tonnes Per Annum (MTPA) of LNG. VG also just sought regulatory approval to begin expanded operations at their Plaquemines LNG export facility ahead of schedule.

Last month VG announced a long term LNG supply agreement with China Gas Holdings.

US energy exporters are seeing demand strengthen off the back of the ongoing disruption to supplies out of the Persian Gulf. Shipments of Natural Gas Liquids (NGLs) which include ethane, propane and butane, are expected to be up 10% this year. Enterprise Products Partners (EPD) is a big beneficiary, along with Targa Resources (TRGP).

China is a big buyer of US ethane, taking around half of US exports. Energy Transfer is expanding its Marcus Hook Terminal in Pennsylvania to meet growing demand.

From the narrow perspective of the midstream sector, there’s ample reason to hold a constructive outlook. Rising real yields combined with record high stocks mean that such optimism is rippling across many other sectors too.

It also seems to us that the mid-terms will represent an inflection point. White House concern for gasoline and diesel prices will be less acute once the votes are in. The weeks following, until the new Congress is sworn in, may represent Trump’s best opportunity to apply maximum military pressure on Iran before the incoming Democrats seek to curtail his freedom of action. Iran’s best negotiating opportunity is now, and they seem disinclined to seize it. Another leg up in oil and global LNG prices seems more likely than not after November 3.

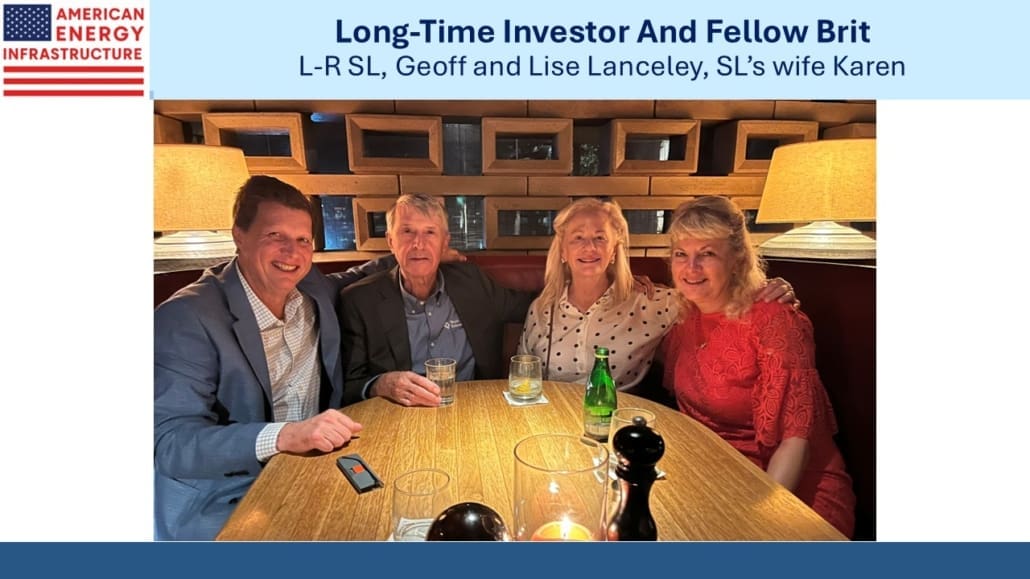
Last week we were on the road seeing long-time investors. Geoff Lanceley, a transplanted Brit living in Houston, has been with us for over a decade. Over the years he and I have enjoyed a few Indian dinners together, coming up with many conservative solutions for the world’s problems. Following a fascinating career that includes stints in the Middle East in the energy sector before moving into asset management, he will be taking a well-earned retirement next May around his 80th birthday. We had a most enjoyable dinner with Geoff and his charming wife Lise and will look forward to seeing them again on our next trip to south Texas.

In New Orleans we enjoyed another visit with Keith Laterrade and his lovely wife Melissa. Every year Keith seems to pick a local restaurant better than the last. This year was Muriel’s at Jackson Square. Keith has also been invested with us for over a decade, to the undoubted benefit of his clients. Keith’s eclectic background includes playing as a goalkeeper many years ago in the English football league. Naturally we found time to discuss Manchester City, for whom he played on a couple of occasions.  and their numerous spending violations which are a huge story there.

Catching up with long-time investors and friends is one of the nicest parts of my job.

We have two funds that seek to profit from this environment:

Energy Mutual Fund Energy ETF


Higher Yields Reflect Positivity

SL Advisors Talks Markets
Higher Yields Reflect Positivity
Loading
/

Midstream had a tough month in September, with the American Energy Infrastructure Index (AEITR) -8.3%, its second worst month in the past five years. Rising treasury yields pressured sectors traditionally owned for their income.  The S&P Utilities ETF (XLU) was –5.9% for the month and is now –5.7% YTD through the third quarter. The Vanguard Real Estate ETF (VNQ) was –6.3% and is now +4.2% YTD. The S&P 500 Low Volatility High Dividend Index was –7.7% and is +4.4% YTD. The Barclays Agg was –2.6% in September and is –2.8% YTD.

The AEITR’s YTD performance of +17.9% is well ahead of other income-generating sectors, even after a lousy month.

The 1.2% increase in ten year treasury yields over the past year has been fully the result of real yields moving higher. Inflation expectations, defined as the difference between ten year nominal treasuries and TIPs (Treasury Inflation Protected Securities) have not budged and sit at around 2.3%.

The University of Michigan survey of consumer expectations has future inflation at around 3%, but similar to the bond market, this figure has been stable.

This is consistent with a positive economic outlook. Real yields have moved up because the market is expecting strong growth.

An important confirmation of this shows up in fund flows. In the twelve months through July, foreign investors bought a record $942BN in US equities and equity funds, while their purchases of US treasuries cooled. China has been steadily reducing their holdings for over a decade, which at $618BN are less than half their peak of $1.3TN in 2013.

It’s also consistent with the S&P500 being +12.8% YTD. In March, weakness in bonds hurt stocks, which were –4.9%. The explanation offered was that the NPVs of growth stocks that dominate the index were acutely sensitive to a higher discount rate on their much higher profits many years out.

Bonds had a worse month in September, but the S&P500 was only –0.4%. Over the past year in eight of twelve months stocks have been up and only two months (March and June) were down by more than 2%.

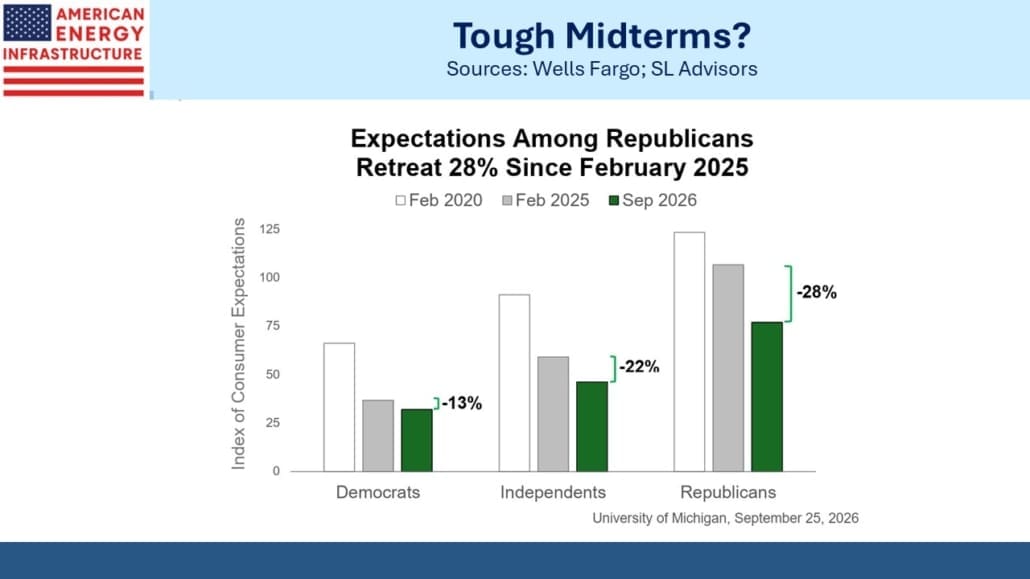
Surveys continue to defy the positive outlook held by investors. The University of Michigan reported that Consumer Expectations fell to 46.3 in September, down 10.4% year-on-year.  Political affiliation skews the result, but the White House will be frustrated to see that Republicans are becoming more pessimistic at a faster rate than Independents or Democrats.

Your blogger, who has never been surveyed, retains his confidence in America’s bright future, which has always been right.

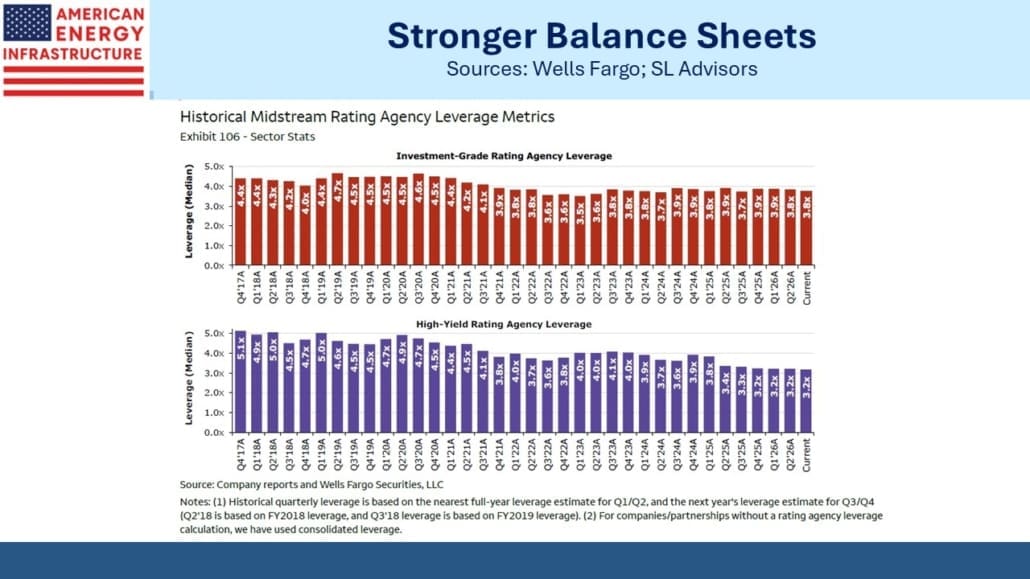
A steady if unheralded improvement in the financial strength of midstream underpins its 20% five-year annual return, handily beating the S&P500 over that period at 13.8%. Leverage has steadily come down, with many companies in the 3.0-3.5 range Debt:EBITDA, down by 0.5X to 1.0X over the past decade.

Years ago, Kinder Morgan (KMI) used to argue that their diversified asset base could support 5.0X. Rating agencies disagreed, and in 2015 KMI cut their $2 annual dividend by 75%. Even now it’s only $1.19.

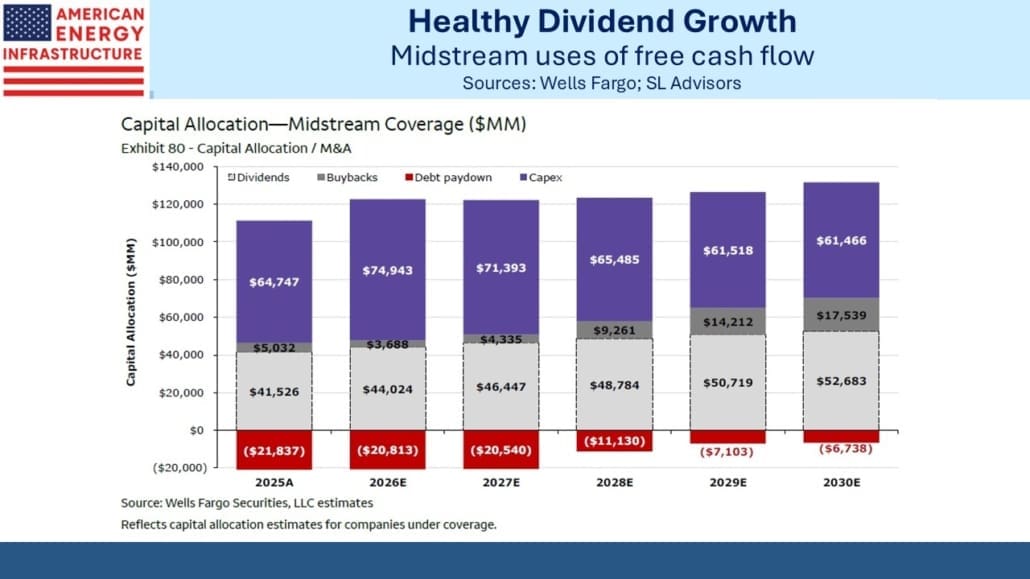
Wells Fargo is projecting 4.9% annual dividend growth for the midstream sector.

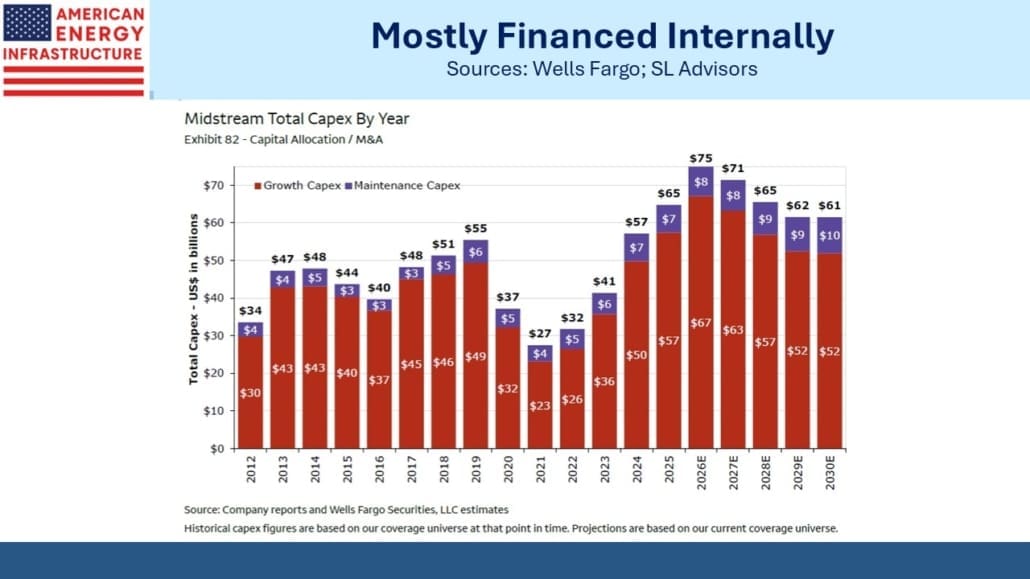
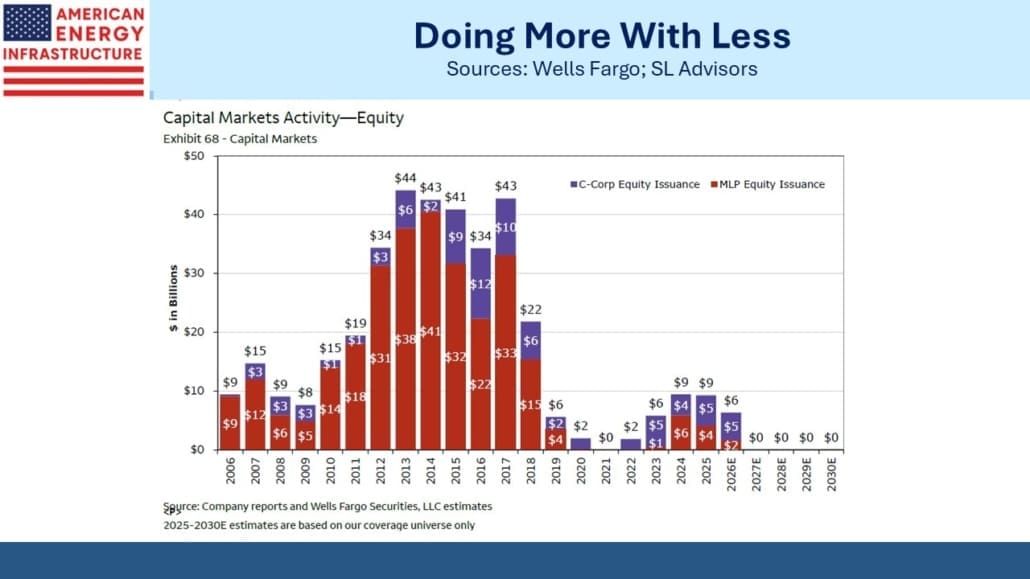
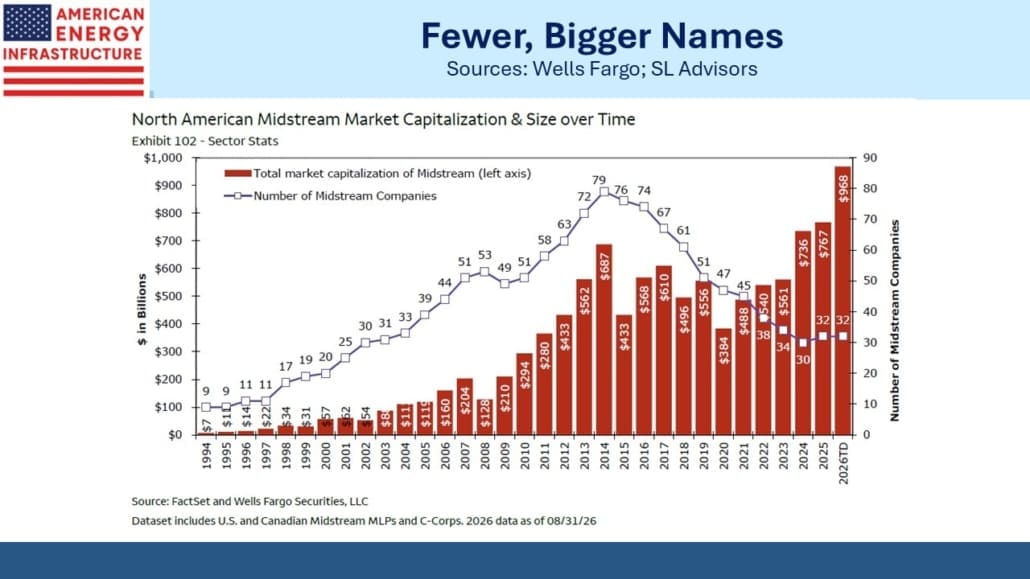
Capex has been creeping up, but in another sign of improved stewardship it’s mostly financed through internally generated cash rather than public equity offerings. Midstream generates far less in capital markets fees for Wall Street than it used to. The industry has grown while the number of names has shrunk. Today it’s mainly an investment grade, large cap sector.

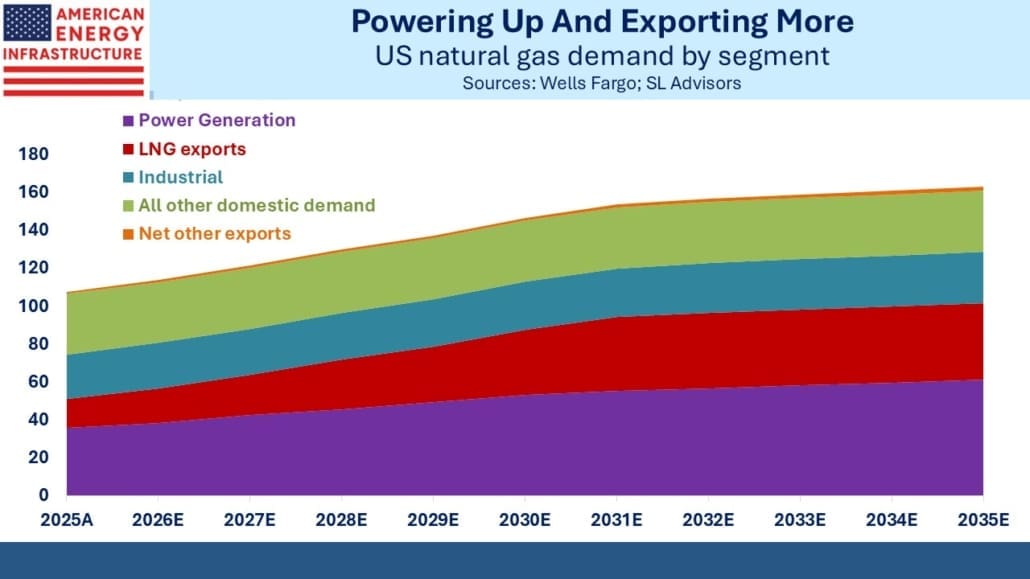
The growth outlook for natural gas remains dominated by increasing exports and greater power generation. Wells Fargo expects feedstock for LNG terminals to more than double by 2035 (10.2% CAGR), while gas for power generation will grow at 5.6% annually.

Consequently, we think midstream remains attractively priced. The rise in real yields that reflects a robust growth outlook is good for midstream companies, which benefit from higher volumes. The Iran war has boosted the outlook for US exporters of hydrocarbons. The weakness in September doesn’t seem justified by the fundamentals.

Just over four years ago Stuart Kirk, then HSBC’s head of Responsible Investment, gave a delightful presentation about the extreme hype over global warming that dominated the left wing and media. He accused presenters of trying to “out-hyperbole” one another, and noted that even though the presenter just before him had warned that humans would not survive, “…no-one ran from the room. In fact, most of you barely looked up from your mobile phones.”

The presentation hastened Kirk’s departure from HSBC, and he now writes a column for the Financial Times.

Since then, the shrill voices warning of the end of the planet have been replaced by more sober consideration that places climate change alongside other major challenges such as malnutrition, access to clean water and reliable electricity. Regulators in the US and EU have reduced the burden on companies to report on potential climate change impacts.

As for Stuart Kirk, he’s moved on to condemn the current fear that fiscal profligacy will condemn us all to penury (see The climate doom-mongers now dread sovereign debt blowouts). He’ll probably find a lot of familiar faces on the other side of this debate.

We have two funds that seek to profit from this environment:

Energy Mutual Fund Energy ETF


Venture Global Moves More Than Needed

SL Advisors Talks Markets
Venture Global Moves More Than Needed
Loading
/

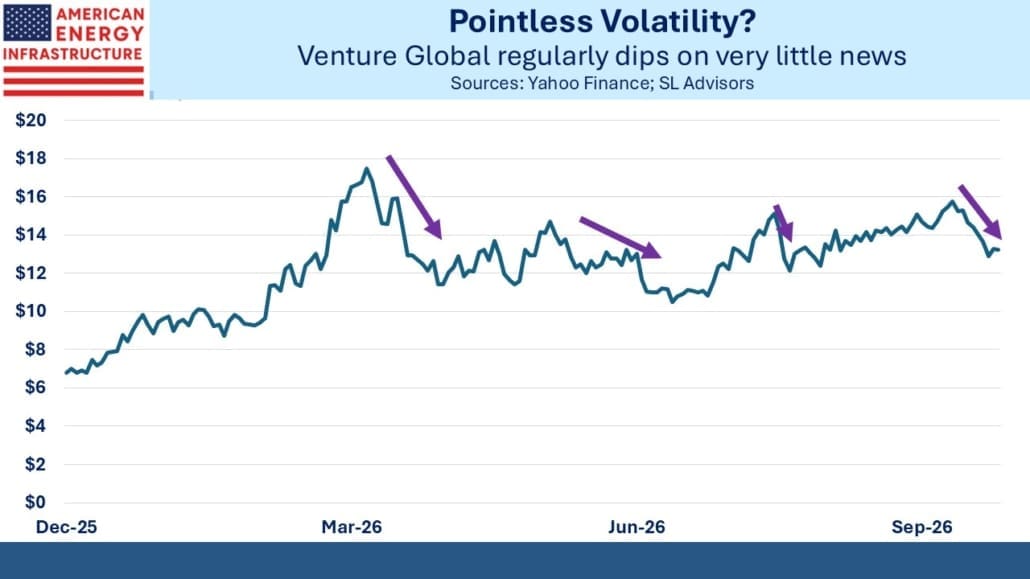
Market making in Venture Global (VG) must be a profitable business. More than most stocks, its price often follows a manic-depressive ride turning on the plausibility of presidential comments about negotiation with Iran. Following each dip as traders quickly conclude Trump’s  tweets on Truth Social are based more on hope than substance, the stock rebounds. It’s dropped more than 15% in a month four times this year.

VG’s prospects improved once Qatar was forced to stop shipments of LNG. That is pretty much all investors need to consider other than the short term profit opportunities from the liquefaction capacity they can access that’s not already committed.

Last week as US energy exporters reeled from another sentiment shift around negotiations, VG dipped below $13, a level it easily exceeded in early March on its way to a high for the year of $17.46 reached on March 27. VG’s business prospects since then have only improved. It’s doubtful Qatar was warning its expectant buyers of LNG that there would still be no shipments six months later. If you want your LNG delivered on time, better to buy American.

But the market has done what markets do, and some perceived last week’s dip as an opportunity.

Predictably, President Trump has thrown his support behind a ban on diesel exports, having already told Ukraine’s President Zelenskyy to stop bombing Russian refineries. This is the proximate cause of the global shortage with the other being the loss of Persian Gulf exports of refined products.

The US produced 4.8 Million Barrels per Day (MMB/D) of Distillate Fuel Oil last year, which includes both diesel and heating oil. We consumed 3.9 MMB/D, exporting the balance. We do import a small amount, mostly in New England from Canada. Distillate Fuel Oil represents 18-20% of domestic petroleum products demand.

The challenges in a ban on diesel exports include that diesel that would be redirected internally is produced near the Gulf Coast where it can be loaded onto ships. There isn’t the pipeline infrastructure readily available to move it elsewhere in the country.

The 1920 Jones Act, which often impedes efforts to move hydrocarbons on water within the US, mandates that goods moved between American ports must travel in ships that are US owned, built and crewed. It’s why Boston imports LNG; left wing energy policies have prevented adding pipeline capacity linking them to Pennsylvania. Instead, it comes from foreign countries because there are no Jones Act-compliant LNG tankers that could ship it from the Gulf coast.

During WWII the country was divided into Petroleum Administration for Defense Districts (PADDs) and the EIA still uses them. PADD1 includes New England. Its imports of distillate fuel oil rise in the Fall/Winter, making this an inopportune time to disrupt their supply.

These imports come from foreign sources, and since the impact of an export ban is likely to push foreign diesel prices up, this region would likely see higher, not lower prices at least initially.

Overall, the friction to the movement of existing diesel fuels caused by an export ban would reduce the expected price benefit. There would be little point in investing in new pipelines to transport diesel from Gulf coast refineries to, say, New England because of the temporary nature of the ban.

Trump’s best bet might be to voice support for a ban without doing much to implement one. Energy Secretary Chris Wright has suggested an export ban might be voluntary, which would allow the Administration to claim some action while avoiding blame for any resulting price distortions.

The Mediterranean vistas from Corfu, where we spent a few days last week, are mercilessly unsullied by wind turbines. Windpower might seem a logical choice for a Greek island with no local sources of coal or gas. In fact, there are no power plants at all on Corfu, which draws almost all its power from the Greek mainland via undersea cables.

EVs are surprisingly uncommon – Greece EV penetration is barely a third of the EU average. The fleet of cars is older than average – Greeks keep their cars longer because they’re poorer. And the charging infrastructure is not as well developed as elsewhere.

Corfu’s energy mix for electricity mirrors Greece since that’s where its power comes from. Natural gas is the biggest source at 37%, not far behind the US. Wind is 22% although as mentioned not from anywhere near Corfu.

Greece’s gas imports have been rising. Over half of their gas consumption is delivered as LNG, and the US is around three quarters of that. In June Greece’s gas importer Atlantic-SEE LNG Trade, expanded an LNG deal with VG.

They’re taking a longer-term view than some of the recent traders in VG stock.

We have two funds that seek to profit from this environment:

Energy Mutual Fund Energy ETF


Scotland Taps Its Windy Coastline

SL Advisors Talks Markets
Scotland Taps Its Windy Coastline
Loading
/

Last week’s blog post about inflation (see Estimating Your Retirement Spending) resonated with quite a few financial advisors. Several noted that persuading clients to accept sufficient exposure to stocks with the goal of maintaining purchasing power is one of their biggest challenges. The examples showing that many retirees will find their spending increases faster than stated inflation was especially well received.

A former colleague from JPMorgan offered some useful insight into housing costs. 40% of homeowners don’t have a mortgage, a group that is overwhelmingly in or near retirement. This insulates them from the approximately third of the CPI that seeks to capture the cost of shelter through the weird concept of Owners’ Equivalent Rent. Its weaknesses are regularly chronicled here (see  Why You Can’t Trust Reported Inflation Numbers).

The top 5% of households by income referenced in last week’s blog are even more likely to be insulated from housing inflation and in many cases downsize – although as I was reminded, some towards the higher end of this cohort increase their household expenses  by adding a second home.

Another reader also noted that the biggest wealth transfer in history is unfolding as baby boomers pass on their wealth to the next generation. For those fortunate beneficiaries, the concerns over retirement purchasing power will be less acute.

The prior week’s blog post on private equity’s discovery of midstream also drew comments (see Private Capital Sees A Cheap Public Market). We think the market doesn’t fully appreciate the cashflow reliability inherent in many midstream businesses. This is what’s drawing in outside capital, with structures that seek to isolate this benefit without imposing any meaningfully higher risk on existing investors.

JPMorgan found that investors in Oneok were critical of a structure that used capital with an IRR of 7.25% or possibly higher to reduce debt yielding around 5%, although the reduced leverage does justify this for some.

Williams Companies (WMB) took a different approach in their partnership with Blackstone by carving out a portion of Behind The Meter (BTM) deals into a separate entity. This approach allows for a valuation of specific assets, potentially at a higher level than when embedded within the overall corporate structure. We think there will be more examples of this which should ultimately help the sector resolve to a higher valuation.

Higher crude oil prices garnered headlines last week, along with record prices for diesel. The continued move higher in global LNG prices has been just as impressive if less widely reported. The European TTF benchmark is above $26 per Million BTU compared with the US at below $3. Exploiting the vast arbitrage is available to those with spare liquefaction capacity, notably Venture Global. Their strategy of retaining some capacity for themselves is allowing them to profit more effectively from today’s opportunity than Cheniere, which has committed 95% through 2035. The two companies offer a different risk profile and exposure to LNG price differentials.

But both stand to benefit over the long run, along with NextDecade from Qatar’s protracted inability to ship LNG out of the Persian Gulf. US hydrocarbon exporters more broadly should see a boost over the long term, including Enterprise Products Partners and Targa Resources for their ability to supply LPGs.

My wife and I are in Europe, home of the world’s most dysfunctional energy policies and consequently some of the highest electricity prices. European natural gas stocks have been running below normal levels for this time of year while prices have inconveniently moved up. Replenishing those stocks in time for winter will likely require government subsidies to avoid the political damage of even higher household fuel bills.

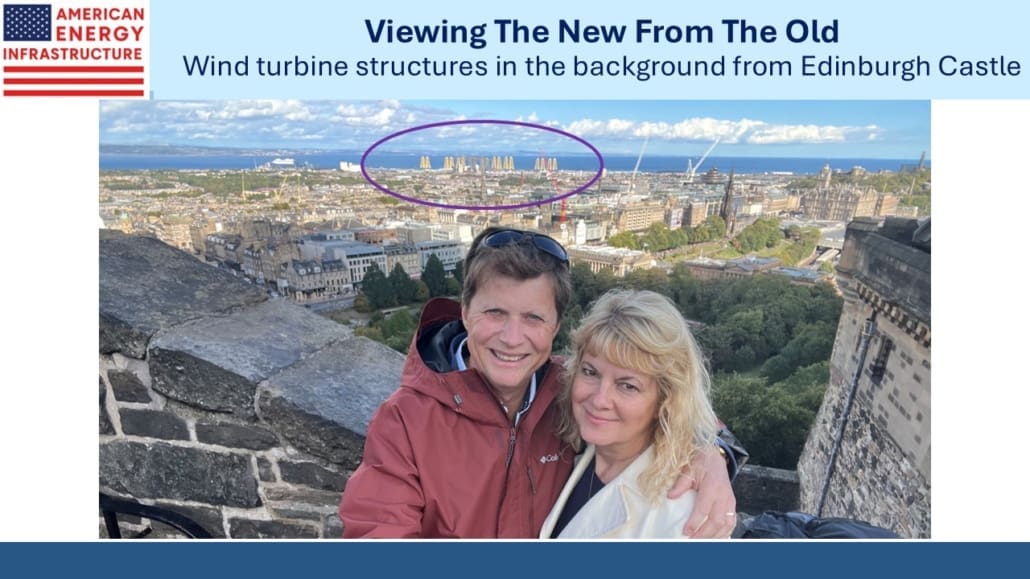
Like much of Europe, Edinburgh, where we visited last week, consumes energy more sparingly. Hotel corridors have motion sensitive lighting. The electric hand-dryers in the washrooms shut off more quickly. Windpower has been relatively successful in the UK, providing over a quarter of the country’s electricity and on some days all of it. Coal has been completely phased out.

Scotland generates more than it can use, and the infrastructure to transmit the excess south to England remains inadequate. Regional pricing doesn’t reflect local abundance, so Scots grumble about subsidizing their Sassenach neighbors with cheap windpower.

Britain’s surrounding waters are reliably windy. We saw several jacket foundations, the steel yellow lattice structures that support wind turbines, lined up on the port in Leith ready to be moved offshore. They’re built in China where coal is the dominant form of energy and shipped from the other side of the world. For decades the North Sea has provided oil and gas. Now it’s also providing electricity.

Household electricity prices in the UK are roughly double the US average, while industry pays two and a half times as much. Renewables are expensive in most of the places they’re deployed at scale around the world, although the US also benefits from cheap natural gas. Around a quarter of UK power comes from gas, but given the prices noted above it’s expensive. With coal reserves exhausted, windpower seems like a sensible option.

Thanks to the shale revolution, America remains the home of cheap energy.

We have two funds that seek to profit from this environment:

Energy Mutual Fund Energy ETF


Estimating Your Retirement Spending

SL Advisors Talks Markets
Estimating Your Retirement Spending
Loading
/

An increasing number of my friends are nearing retirement if not already there. Many spent years working for large corporations, and few miss it. I have no similar plans – running your own business is the most meaningful paid activity I’ve experienced, and I can’t imagine any alternative could be as fulfilling.

My tribe of energy investors and golf club members is not representative of the general population. Nor is the subset of retirees who have enjoyed professional success to reach that stage. But they have more in common with the readers of this blog, and by extension to many of our clients.

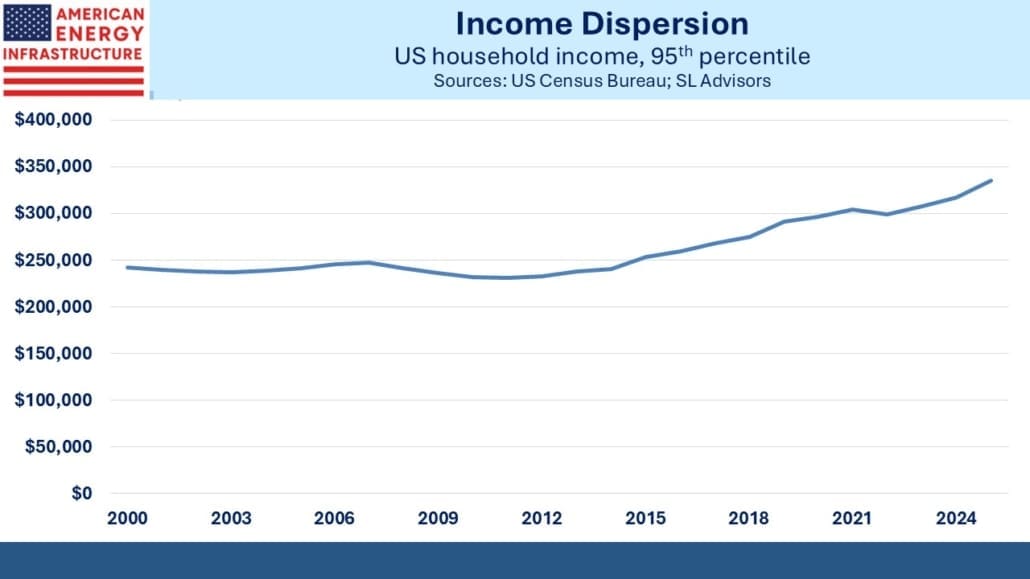
According to the Census Bureau, a male in his early 60s has on average twenty years of life remaining and a one in four chance of reaching 90. But longevity is correlated with income. Wealthier people enjoy better health and make better life choices. $336K in annual household income gets you into the top 5% of households and adds another five years of life expectancy.

Here begins the bet on how one’s income will grow compared with inflation. The 95th percentile of household net worth is $3.8 million according to the Federal Reserve’s Survey of Consumer Finances. A household at the 95th percentile of net worth and income is earning (and presumably spending) around a tenth of this annually. Even assuming a 3% after tax return, that retirement pot will shrink over time. To paraphrase Mr. Micawber in Dickens’ David Copperfield, the difference between outliving your savings and not is the difference between happiness and misery.

The spread between the rate at which your spending outgrows the income from your retirement assets will heavily impact the odds of later financial happiness. Over a quarter century, as little as a 1% adverse spread will leave you with 22% less purchasing power. A 3% spread will cut your purchasing power in half.

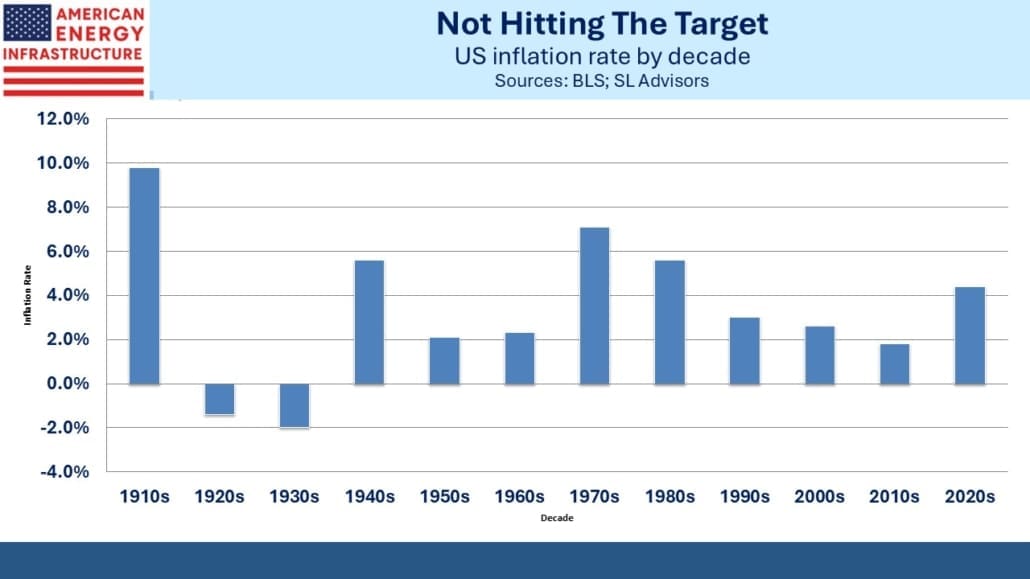
The case for assuming 2% inflation is extraordinarily weak. Since World War II, inflation has averaged 3.5% and has rarely been below 2%. Fiscal profligacy such as ours has for centuries ultimately been resolved through debt monetization and currency debasement, a regular theme of this blog (see US Explores The Limits On Spending).

Politicians long ago quit recommending fiscal solutions. Tax hikes and spending cuts quickly turn a legislator into a paid lobbyist after a lost election. It is democratic if unwise.

And even his biggest fans must concede that President Trump is not a hard money man. If the FOMC raises rates by the end of the year as is currently priced in to the futures market, the White House response will be voluble and bombastic.

The Democrats caused the biggest inflation surge in fifty years with the uber-stimulus in their comically named Inflation Reduction Act.

Neither party is credible on maintaining stable prices.

Inflation has been above 3% for the past five years. It’s an especially poor measure of how much spending has increased for the top 5%. Inflation statistics intentionally adjust for better products and services (known as hedonic quality adjustments). The CPI and its cousins only set out to measure the cost increase of a basket of goods and services of constant utility, matching which will leave your living standard slipping against your peers (see Economists Having Fun With Inflation).

Moreover, the top 5% consume a basket of goods and services quite different from the average household. Surveys and Bureau of Labor Statistics data show that over the past five years the cost of fine dining, business class flights and live entertainment have all grown at around 6-8% per annum. Because, dear reader, you are fortunate to be richer than the typical American, your inflation rate is not close to what the government says it is.

What should our atypical retiree assume for her annual increase in living expenses?

2% seems ruinously optimistic, a level we’ve rarely hit and at odds with our fiscal outlook in spite of Fed Chair Kevin Warsh’s stated determination to retain it as the Fed’s goal.

4% is the average since 2021, but if the rest of the decade is similar, this still leaves our retiree steadily losing purchasing power.

5% is probably the lowest assumed inflation rate for someone in the top 5% of household income that wants to avoid feeling steadily poorer every year. 95th percentile household income has accelerated in recent years, growing at 2.9% over the past decade and 5.7% last year. Assuming a constant savings rate implies that the basket of goods and services consumed by that cohort has risen at the same rate.

Regular readers know that these blog posts guide to the buying opportunity that is midstream energy infrastructure. There are few asset classes that can match a 5% annual increase in living expenses. But a 4% dividend yield combined with a 3-4% dividend growth rate offers a decent chance of providing a commensurate after-tax return, unless you live in one of those blue, high tax states.

We have two funds that seek to profit from this environment:

Energy Mutual Fund Energy ETF
 

image_pdfimage_print