Betting On High LNG Prices


/
Venture Global (VG) reported 3Q26 earnings of $2.5BN last Tuesday, making its $30BN market cap look oddly cheap. A one-time interest rate swap gain of $1.4BN was significant, but even adjusting for that the stock closed at less than 7X annualized earnings following their quarterly release. After a day’s consideration, analyst forecasts and the stock price duly rose, finishing the week with a market cap of $33BN. Their FY EBITDA guidance of $10-10.3BN sits comfortably ahead of Cheniere’s $8.75-9.25BN, which nonetheless is worth almost twice as much.
Cheniere still has more liquefaction capacity, projecting 56-58 million tonnes for next year. Both companies continue to add capacity, with VG expecting to exit next year at 35-40 Million Tonnes per Annum (MTPA) with a long-term goal to reach 100 MTPA by 2030.
The reputational hit from VG’s conveniently timed delay in LNG shipments when Russia invaded Ukraine (see Nothing Ventured, Nothing Gained) left many buyers wary and has meant Cheniere can charge slightly higher liquefaction fees, which are typically in the $2-2.50 range per Million BTUs (MMBTUs).
The big difference between the two companies is that VG is more willing to retain capacity for themselves, which pays big dividends at times like this when European and Asian benchmarks are so much higher than the US Henry Hub. Cheniere has presold 95% of their liquefaction capacity through 2035, which creates a lot of cash flow certainty.
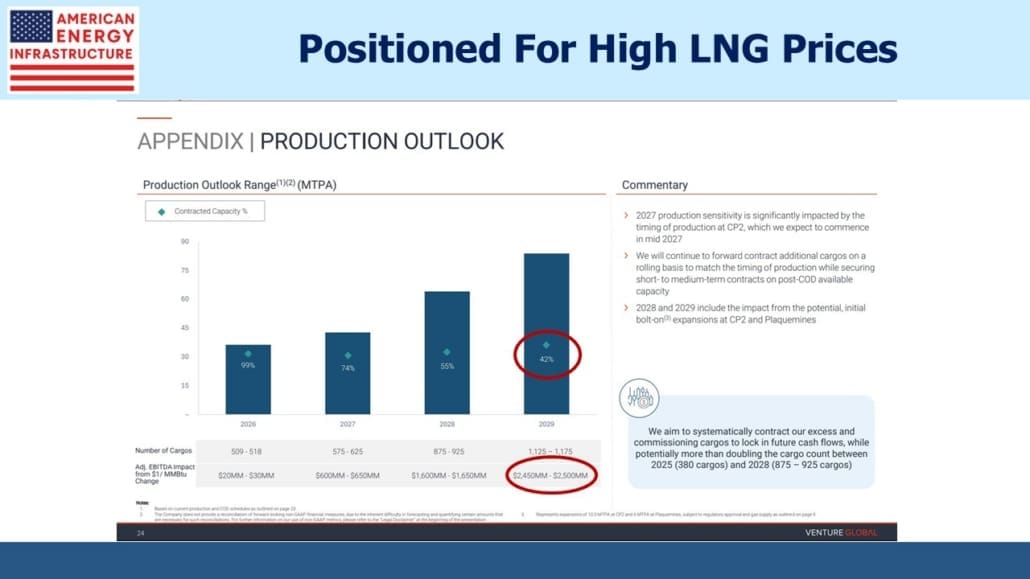
For the remainder of this year VG is expecting to earn $21-22 per MMBTUs on uncommitted liquefaction capacity, which shows how profitable that strategy is currently. VG is 74% contracted just for next year. For 2029, they’re 42% contracted. A $1 per MMBTU change in their liquefaction fee is worth $20-30MM for the remainder of this year, but a whopping $2.45-2.5BN by 2029. It’s this uncertainty that causes VG to trade at a substantial discount to Cheniere.
VG does plan to contract out substantial amounts of capacity. But the stock will always represent more of a bet on the future spread between international and domestic gas prices than Cheniere.
Spiro Dounis at Citi just raised his price target from $17 to $20, projecting a more than 50% one year return. There aren’t many $33BN stocks with that kind of upside potential.
Qatar lost their first LNG customer last week. Poland’s Orlen SA canceled a 1 MTPA agreement that was supposed to run through 2034. They evidently tired of Qatar’s ongoing delivery failures, which have continued long enough to allow Orlen’s exercise of their cancelation option. If other buyers similarly use the extended force majeure to exit their agreements, it will cast further doubt on Qatar’s expansion plans to add over 80% to existing liquefaction capacity.
QatarEnergy continues to seek long term purchase agreements with US suppliers, with NextDecade currently negotiating to provide 2 MTPA from TraIn 6 at their Rio Grande facility. Trains 1-5 are under construction, but Train 6 hasn’t yet received final investment decision. A deal with Qatar would probably be enough to get that project approved.
Qatar’s deal spree with Cheniere and Venture Global suggests they’re lining up alternative supply to address buyers’ fears of future disruptions. Qatar may also plan to trade those shipments, reasoning that a future closure of the Strait of Hormuz would allow them to profit from higher global prices the way VG has done this year.
Moreover, it’s Qatar’s planned expansion that is driving the fears of an LNG supply glut, causing some analysts even now to overlook the upside in US exporters. If those expansion plans are shelved, the glut fears will evaporate making the deals Qatar recently signed to buy from the US worth a lot more. They’ve quickly become America’s biggest LNG buyer, with interesting optionality as a result.
For those following NextDecade and their progress building their Rio Grande liquefaction facility in SW Texas, here’s a brief video.
Last week the sector rebounded, having offered an entry point following the election swoon. This was in spite of ten year treasury yields jumping 23 bps due to further bad inflation numbers. The sector’s resilience to weaker bond prices was in marked contrast to September.
As we noted in The Blue Wave there’s little discernible relationship between energy sector returns and the party in power, even though its executives and investors tend to be Republican.
Some Republicans wrongly blame popular opposition to AI for their drubbing (it was the economy, stupid). It does strengthen the case for Behind The Meter (BTM) solutions to power generation, since data centers will need to operate without affecting local electricity prices.
TC Energy (TRP) is joining Williams Companies and Energy Transfer in providing BTM solutions. They recently disclosed a doubling of their capex backlog to C$40BN of which C$15BN is in their Power & Energy Solutions segment. BTM is coming to Canada too.
We have two funds that seek to profit from this environment:

Important Disclosures
The information provided is for informational purposes only and investors should determine for themselves whether a particular service, security or product is suitable for their investment needs. The information contained herein is not complete, may not be current, is subject to change, and is subject to, and qualified in its entirety by, the more complete disclosures, risk factors and other terms that are contained in the disclosure, prospectus, and offering. Certain information herein has been obtained from third party sources and, although believed to be reliable, has not been independently verified and its accuracy or completeness cannot be guaranteed. No representation is made with respect to the accuracy, completeness or timeliness of this information. Nothing provided on this site constitutes tax advice. Individuals should seek the advice of their own tax advisor for specific information regarding tax consequences of investments. Investments in securities entail risk and are not suitable for all investors. This site is not a recommendation nor an offer to sell (or solicitation of an offer to buy) securities in the United States or in any other jurisdiction.
References to indexes and benchmarks are hypothetical illustrations of aggregate returns and do not reflect the performance of any actual investment. Investors cannot invest in an index and do not reflect the deduction of the advisor’s fees or other trading expenses. There can be no assurance that current investments will be profitable. Actual realized returns will depend on, among other factors, the value of assets and market conditions at the time of disposition, any related transaction costs, and the timing of the purchase. Indexes and benchmarks may not directly correlate or only partially relate to portfolios managed by SL Advisors as they have different underlying investments and may use different strategies or have different objectives than portfolios managed by SL Advisors (e.g. The Alerian index is a group MLP securities in the oil and gas industries. Portfolios may not include the same investments that are included in the Alerian Index. The S & P Index does not directly relate to investment strategies managed by SL Advisers.)
This site may contain forward-looking statements relating to the objectives, opportunities, and the future performance of the U.S. market generally. Forward-looking statements may be identified by the use of such words as; “believe,” “expect,” “anticipate,” “should,” “planned,” “estimated,” “potential” and other similar terms. Examples of forward-looking statements include, but are not limited to, estimates with respect to financial condition, results of operations, and success or lack of success of any particular investment strategy. All are subject to various factors, including, but not limited to general and local economic conditions, changing levels of competition within certain industries and markets, changes in interest rates, changes in legislation or regulation, and other economic, competitive, governmental, regulatory and technological factors affecting a portfolio’s operations that could cause actual results to differ materially from projected results. Such statements are forward-looking in nature and involves a number of known and unknown risks, uncertainties and other factors, and accordingly, actual results may differ materially from those reflected or contemplated in such forward-looking statements. Prospective investors are cautioned not to place undue reliance on any forward-looking statements or examples. None of SL Advisors LLC or any of its affiliates or principals nor any other individual or entity assumes any obligation to update any forward-looking statements as a result of new information, subsequent events or any other circumstances. All statements made herein speak only as of the date that they were made. r
Certain hyperlinks or referenced websites on the Site, if any, are for your convenience and forward you to third parties’ websites, which generally are recognized by their top level domain name. Any descriptions of, references to, or links to other products, publications or services does not constitute an endorsement, authorization, sponsorship by or affiliation with SL Advisors LLC with respect to any linked site or its sponsor, unless expressly stated by SL Advisors LLC. Any such information, products or sites have not necessarily been reviewed by SL Advisors LLC and are provided or maintained by third parties over whom SL Advisors LLC exercise no control. SL Advisors LLC expressly disclaim any responsibility for the content, the accuracy of the information, and/or quality of products or services provided by or advertised on these third-party sites.
All investment strategies have the potential for profit or loss. Different types of investments involve varying degrees of risk, and there can be no assurance that any specific investment will be suitable or profitable for a client’s investment portfolio.
Past performance of the American Energy Independence Index is not indicative of future returns.
Leave a Reply
Want to join the discussion?Feel free to contribute!