It’s Not Inflation, For Now


/
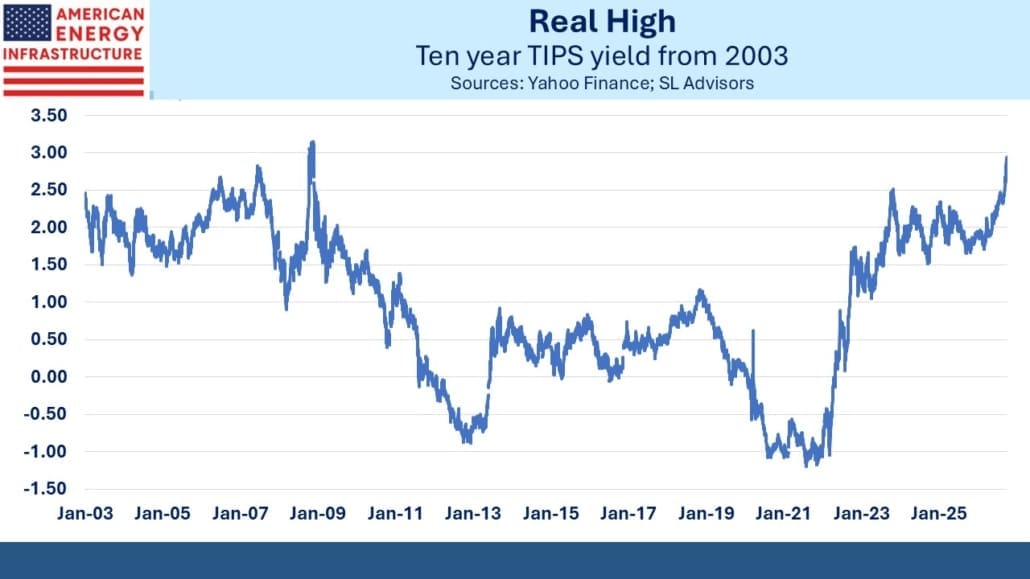
Inflation fears are the widely held explanation for the continued rise in bond yields. This strikes us as an inadequate response that doesn’t correspond with the facts. Inflation expectations are not budging – either as reflected in the TIPS market or in survey data. Real yields are at their highest since the Great Financial Crisis, and it’s their increase that is fully responsible for the jump in bond yields over the past year. A significant difference with 2008 is that today stocks are close to record highs. Inflation fears are not visible, for now anyway (see Higher Yields Reflect Positivity).
That’s not to say that the market is cheap. Measures such as the Shiller Cyclically Adjusted Price Earnings (CAPE) or the Equity Risk Premium are showing valuations to be high, as we noted in June. But these measures are not good timing tools.
There is plenty to worry about – isn’t there always? Aside from the known big risks (no need to list them, we know what they are), future inflation should be of great concern to savers everywhere. Higher inflation, enabling negative real yields on government debt, is the likely resolution of our looming fiscal catastrophe. It’s how governments repay debt in devalued currency, performing a stealth default rather than a sudden one. It’s been used many times over the centuries.
But investors are showing no signs of concern about future inflation for now. In any case, CPI or the Fed’s preferred PCE deflator, are both losing their utility as a planning tool. They remain critical to forecasting interest rate policy and inflation adjustments. But inflation statistics are massaged in so many ways that they now have little to do with how consumers experience a rising cost of living.
BLS economists and the Fed inhabit a theoretical world where they subtract out quality improvements, extreme price changes, food and energy and don’t directly measure the cost of owning a home (see What’s Your Inflation Rate?). They’re not much use.
Today’s bond yields and stock prices reflect an optimistic view of future economic growth and profits. Bonds had to fall in order to offer an increased return to compete with stocks. There’s little sign that investors are at all worried.
Midstream energy, which we believe remains cheap, is providing plenty of reasons for optimism. Venture Global (VG) recently signed a 20-year deal with Conoco-Phillips to provide 1 Million Tonnes Per Annum (MTPA) of LNG. VG also just sought regulatory approval to begin expanded operations at their Plaquemines LNG export facility ahead of schedule.
Last month VG announced a long term LNG supply agreement with China Gas Holdings.
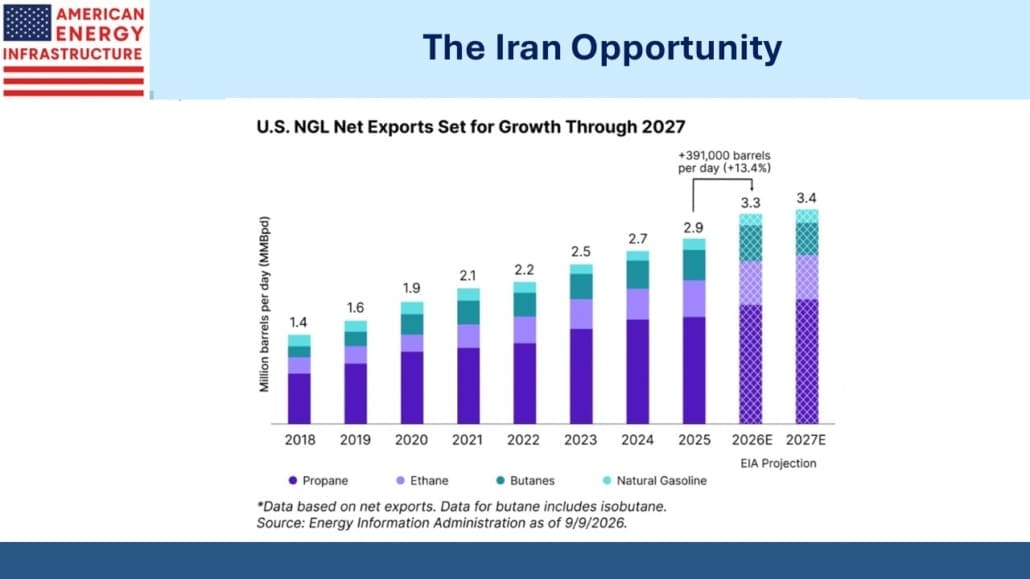
US energy exporters are seeing demand strengthen off the back of the ongoing disruption to supplies out of the Persian Gulf. Shipments of Natural Gas Liquids (NGLs) which include ethane, propane and butane, are expected to be up 10% this year. Enterprise Products Partners (EPD) is a big beneficiary, along with Targa Resources (TRGP).
China is a big buyer of US ethane, taking around half of US exports. Energy Transfer is expanding its Marcus Hook Terminal in Pennsylvania to meet growing demand.
From the narrow perspective of the midstream sector, there’s ample reason to hold a constructive outlook. Rising real yields combined with record high stocks mean that such optimism is rippling across many other sectors too.
It also seems to us that the mid-terms will represent an inflection point. White House concern for gasoline and diesel prices will be less acute once the votes are in. The weeks following, until the new Congress is sworn in, may represent Trump’s best opportunity to apply maximum military pressure on Iran before the incoming Democrats seek to curtail his freedom of action. Iran’s best negotiating opportunity is now, and they seem disinclined to seize it. Another leg up in oil and global LNG prices seems more likely than not after November 3.
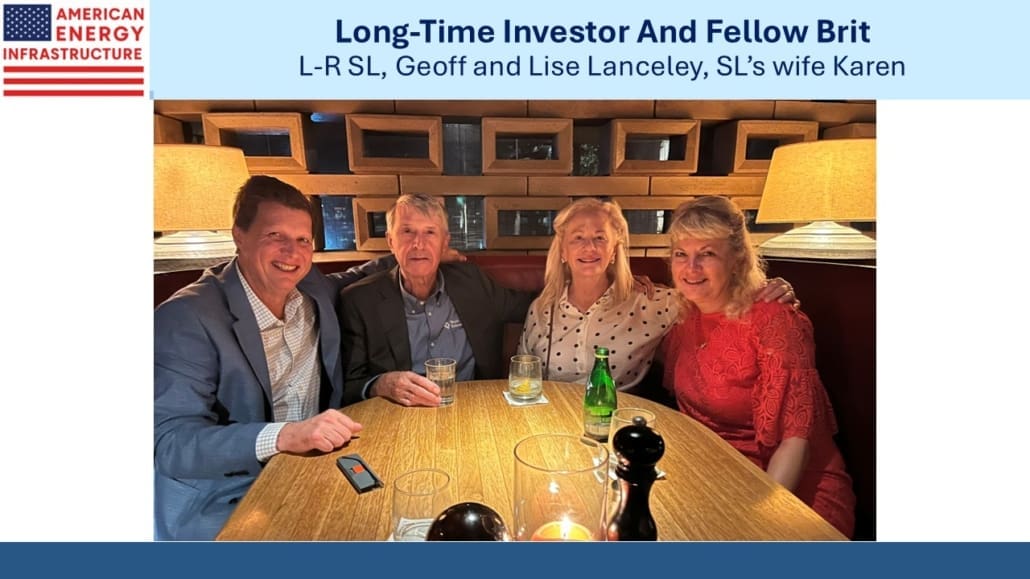
Last week we were on the road seeing long-time investors. Geoff Lanceley, a transplanted Brit living in Houston, has been with us for over a decade. Over the years he and I have enjoyed a few Indian dinners together, coming up with many conservative solutions for the world’s problems. Following a fascinating career that includes stints in the Middle East in the energy sector before moving into asset management, he will be taking a well-earned retirement next May around his 80th birthday. We had a most enjoyable dinner with Geoff and his charming wife Lise and will look forward to seeing them again on our next trip to south Texas.
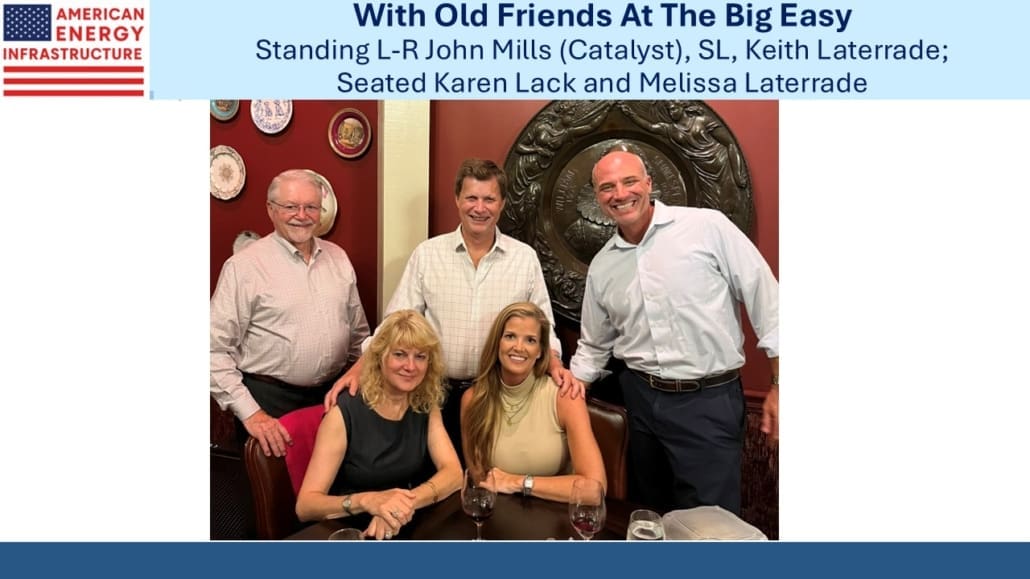
In New Orleans we enjoyed another visit with Keith Laterrade and his lovely wife Melissa. Every year Keith seems to pick a local restaurant better than the last. This year was Muriel’s at Jackson Square. Keith has also been invested with us for over a decade, to the undoubted benefit of his clients. Keith’s eclectic background includes playing as a goalkeeper many years ago in the English football league. Naturally we found time to discuss Manchester City, for whom he played on a couple of occasions. and their numerous spending violations which are a huge story there.
Catching up with long-time investors and friends is one of the nicest parts of my job.
We have two funds that seek to profit from this environment:
Important Disclosures
The information provided is for informational purposes only and investors should determine for themselves whether a particular service, security or product is suitable for their investment needs. The information contained herein is not complete, may not be current, is subject to change, and is subject to, and qualified in its entirety by, the more complete disclosures, risk factors and other terms that are contained in the disclosure, prospectus, and offering. Certain information herein has been obtained from third party sources and, although believed to be reliable, has not been independently verified and its accuracy or completeness cannot be guaranteed. No representation is made with respect to the accuracy, completeness or timeliness of this information. Nothing provided on this site constitutes tax advice. Individuals should seek the advice of their own tax advisor for specific information regarding tax consequences of investments. Investments in securities entail risk and are not suitable for all investors. This site is not a recommendation nor an offer to sell (or solicitation of an offer to buy) securities in the United States or in any other jurisdiction.
References to indexes and benchmarks are hypothetical illustrations of aggregate returns and do not reflect the performance of any actual investment. Investors cannot invest in an index and do not reflect the deduction of the advisor’s fees or other trading expenses. There can be no assurance that current investments will be profitable. Actual realized returns will depend on, among other factors, the value of assets and market conditions at the time of disposition, any related transaction costs, and the timing of the purchase. Indexes and benchmarks may not directly correlate or only partially relate to portfolios managed by SL Advisors as they have different underlying investments and may use different strategies or have different objectives than portfolios managed by SL Advisors (e.g. The Alerian index is a group MLP securities in the oil and gas industries. Portfolios may not include the same investments that are included in the Alerian Index. The S & P Index does not directly relate to investment strategies managed by SL Advisers.)
This site may contain forward-looking statements relating to the objectives, opportunities, and the future performance of the U.S. market generally. Forward-looking statements may be identified by the use of such words as; “believe,” “expect,” “anticipate,” “should,” “planned,” “estimated,” “potential” and other similar terms. Examples of forward-looking statements include, but are not limited to, estimates with respect to financial condition, results of operations, and success or lack of success of any particular investment strategy. All are subject to various factors, including, but not limited to general and local economic conditions, changing levels of competition within certain industries and markets, changes in interest rates, changes in legislation or regulation, and other economic, competitive, governmental, regulatory and technological factors affecting a portfolio’s operations that could cause actual results to differ materially from projected results. Such statements are forward-looking in nature and involves a number of known and unknown risks, uncertainties and other factors, and accordingly, actual results may differ materially from those reflected or contemplated in such forward-looking statements. Prospective investors are cautioned not to place undue reliance on any forward-looking statements or examples. None of SL Advisors LLC or any of its affiliates or principals nor any other individual or entity assumes any obligation to update any forward-looking statements as a result of new information, subsequent events or any other circumstances. All statements made herein speak only as of the date that they were made. r
Certain hyperlinks or referenced websites on the Site, if any, are for your convenience and forward you to third parties’ websites, which generally are recognized by their top level domain name. Any descriptions of, references to, or links to other products, publications or services does not constitute an endorsement, authorization, sponsorship by or affiliation with SL Advisors LLC with respect to any linked site or its sponsor, unless expressly stated by SL Advisors LLC. Any such information, products or sites have not necessarily been reviewed by SL Advisors LLC and are provided or maintained by third parties over whom SL Advisors LLC exercise no control. SL Advisors LLC expressly disclaim any responsibility for the content, the accuracy of the information, and/or quality of products or services provided by or advertised on these third-party sites.
All investment strategies have the potential for profit or loss. Different types of investments involve varying degrees of risk, and there can be no assurance that any specific investment will be suitable or profitable for a client’s investment portfolio.
Past performance of the American Energy Independence Index is not indicative of future returns.
Leave a Reply
Want to join the discussion?Feel free to contribute!