Venture Global Moves More Than Needed


/
Market making in Venture Global (VG) must be a profitable business. More than most stocks, its price often follows a manic-depressive ride turning on the plausibility of presidential comments about negotiation with Iran. Following each dip as traders quickly conclude Trump’s tweets on Truth Social are based more on hope than substance, the stock rebounds. It’s dropped more than 15% in a month four times this year.
VG’s prospects improved once Qatar was forced to stop shipments of LNG. That is pretty much all investors need to consider other than the short term profit opportunities from the liquefaction capacity they can access that’s not already committed.
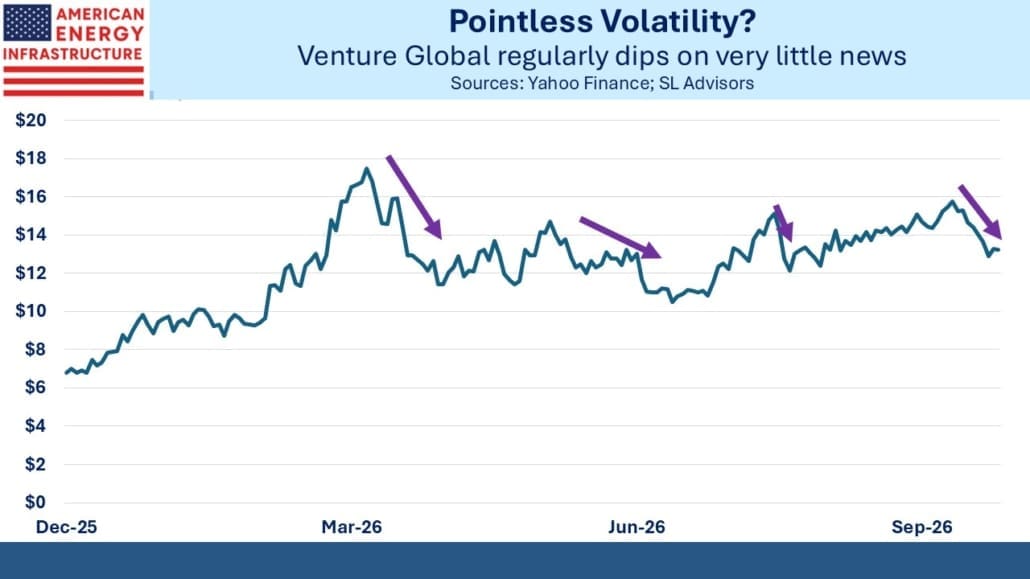
Last week as US energy exporters reeled from another sentiment shift around negotiations, VG dipped below $13, a level it easily exceeded in early March on its way to a high for the year of $17.46 reached on March 27. VG’s business prospects since then have only improved. It’s doubtful Qatar was warning its expectant buyers of LNG that there would still be no shipments six months later. If you want your LNG delivered on time, better to buy American.
But the market has done what markets do, and some perceived last week’s dip as an opportunity.
Predictably, President Trump has thrown his support behind a ban on diesel exports, having already told Ukraine’s President Zelenskyy to stop bombing Russian refineries. This is the proximate cause of the global shortage with the other being the loss of Persian Gulf exports of refined products.
The US produced 4.8 Million Barrels per Day (MMB/D) of Distillate Fuel Oil last year, which includes both diesel and heating oil. We consumed 3.9 MMB/D, exporting the balance. We do import a small amount, mostly in New England from Canada. Distillate Fuel Oil represents 18-20% of domestic petroleum products demand.
The challenges in a ban on diesel exports include that diesel that would be redirected internally is produced near the Gulf Coast where it can be loaded onto ships. There isn’t the pipeline infrastructure readily available to move it elsewhere in the country.
The 1920 Jones Act, which often impedes efforts to move hydrocarbons on water within the US, mandates that goods moved between American ports must travel in ships that are US owned, built and crewed. It’s why Boston imports LNG; left wing energy policies have prevented adding pipeline capacity linking them to Pennsylvania. Instead, it comes from foreign countries because there are no Jones Act-compliant LNG tankers that could ship it from the Gulf coast.
During WWII the country was divided into Petroleum Administration for Defense Districts (PADDs) and the EIA still uses them. PADD1 includes New England. Its imports of distillate fuel oil rise in the Fall/Winter, making this an inopportune time to disrupt their supply.
These imports come from foreign sources, and since the impact of an export ban is likely to push foreign diesel prices up, this region would likely see higher, not lower prices at least initially.
Overall, the friction to the movement of existing diesel fuels caused by an export ban would reduce the expected price benefit. There would be little point in investing in new pipelines to transport diesel from Gulf coast refineries to, say, New England because of the temporary nature of the ban.
Trump’s best bet might be to voice support for a ban without doing much to implement one. Energy Secretary Chris Wright has suggested an export ban might be voluntary, which would allow the Administration to claim some action while avoiding blame for any resulting price distortions.
The Mediterranean vistas from Corfu, where we spent a few days last week, are mercilessly unsullied by wind turbines. Windpower might seem a logical choice for a Greek island with no local sources of coal or gas. In fact, there are no power plants at all on Corfu, which draws almost all its power from the Greek mainland via undersea cables.
EVs are surprisingly uncommon – Greece EV penetration is barely a third of the EU average. The fleet of cars is older than average – Greeks keep their cars longer because they’re poorer. And the charging infrastructure is not as well developed as elsewhere.
Corfu’s energy mix for electricity mirrors Greece since that’s where its power comes from. Natural gas is the biggest source at 37%, not far behind the US. Wind is 22% although as mentioned not from anywhere near Corfu.
Greece’s gas imports have been rising. Over half of their gas consumption is delivered as LNG, and the US is around three quarters of that. In June Greece’s gas importer Atlantic-SEE LNG Trade, expanded an LNG deal with VG.
They’re taking a longer-term view than some of the recent traders in VG stock.
We have two funds that seek to profit from this environment:
Important Disclosures
The information provided is for informational purposes only and investors should determine for themselves whether a particular service, security or product is suitable for their investment needs. The information contained herein is not complete, may not be current, is subject to change, and is subject to, and qualified in its entirety by, the more complete disclosures, risk factors and other terms that are contained in the disclosure, prospectus, and offering. Certain information herein has been obtained from third party sources and, although believed to be reliable, has not been independently verified and its accuracy or completeness cannot be guaranteed. No representation is made with respect to the accuracy, completeness or timeliness of this information. Nothing provided on this site constitutes tax advice. Individuals should seek the advice of their own tax advisor for specific information regarding tax consequences of investments. Investments in securities entail risk and are not suitable for all investors. This site is not a recommendation nor an offer to sell (or solicitation of an offer to buy) securities in the United States or in any other jurisdiction.
References to indexes and benchmarks are hypothetical illustrations of aggregate returns and do not reflect the performance of any actual investment. Investors cannot invest in an index and do not reflect the deduction of the advisor’s fees or other trading expenses. There can be no assurance that current investments will be profitable. Actual realized returns will depend on, among other factors, the value of assets and market conditions at the time of disposition, any related transaction costs, and the timing of the purchase. Indexes and benchmarks may not directly correlate or only partially relate to portfolios managed by SL Advisors as they have different underlying investments and may use different strategies or have different objectives than portfolios managed by SL Advisors (e.g. The Alerian index is a group MLP securities in the oil and gas industries. Portfolios may not include the same investments that are included in the Alerian Index. The S & P Index does not directly relate to investment strategies managed by SL Advisers.)
This site may contain forward-looking statements relating to the objectives, opportunities, and the future performance of the U.S. market generally. Forward-looking statements may be identified by the use of such words as; “believe,” “expect,” “anticipate,” “should,” “planned,” “estimated,” “potential” and other similar terms. Examples of forward-looking statements include, but are not limited to, estimates with respect to financial condition, results of operations, and success or lack of success of any particular investment strategy. All are subject to various factors, including, but not limited to general and local economic conditions, changing levels of competition within certain industries and markets, changes in interest rates, changes in legislation or regulation, and other economic, competitive, governmental, regulatory and technological factors affecting a portfolio’s operations that could cause actual results to differ materially from projected results. Such statements are forward-looking in nature and involves a number of known and unknown risks, uncertainties and other factors, and accordingly, actual results may differ materially from those reflected or contemplated in such forward-looking statements. Prospective investors are cautioned not to place undue reliance on any forward-looking statements or examples. None of SL Advisors LLC or any of its affiliates or principals nor any other individual or entity assumes any obligation to update any forward-looking statements as a result of new information, subsequent events or any other circumstances. All statements made herein speak only as of the date that they were made. r
Certain hyperlinks or referenced websites on the Site, if any, are for your convenience and forward you to third parties’ websites, which generally are recognized by their top level domain name. Any descriptions of, references to, or links to other products, publications or services does not constitute an endorsement, authorization, sponsorship by or affiliation with SL Advisors LLC with respect to any linked site or its sponsor, unless expressly stated by SL Advisors LLC. Any such information, products or sites have not necessarily been reviewed by SL Advisors LLC and are provided or maintained by third parties over whom SL Advisors LLC exercise no control. SL Advisors LLC expressly disclaim any responsibility for the content, the accuracy of the information, and/or quality of products or services provided by or advertised on these third-party sites.
All investment strategies have the potential for profit or loss. Different types of investments involve varying degrees of risk, and there can be no assurance that any specific investment will be suitable or profitable for a client’s investment portfolio.
Past performance of the American Energy Independence Index is not indicative of future returns.
Leave a Reply
Want to join the discussion?Feel free to contribute!