Scotland Taps Its Windy Coastline
Last week’s blog post about inflation (see Estimating Your Retirement Spending) resonated with quite a few financial advisors. Several noted that persuading clients to accept sufficient exposure to stocks with the goal of maintaining purchasing power is one of their biggest challenges. The examples showing that many retirees will find their spending increases faster than stated inflation was especially well received.
A former colleague from JPMorgan offered some useful insight into housing costs. 40% of homeowners don’t have a mortgage, a group that is overwhelmingly in or near retirement. This insulates them from the approximately third of the CPI that seeks to capture the cost of shelter through the weird concept of Owners’ Equivalent Rent. Its weaknesses are regularly chronicled here (see Why You Can’t Trust Reported Inflation Numbers).
The top 5% of households by income referenced in last week’s blog are even more likely to be insulated from housing inflation and in many cases downsize – although as I was reminded, some towards the higher end of this cohort increase their household expenses by adding a second home.
Another reader also noted that the biggest wealth transfer in history is unfolding as baby boomers pass on their wealth to the next generation. For those fortunate beneficiaries, the concerns over retirement purchasing power will be less acute.
The prior week’s blog post on private equity’s discovery of midstream also drew comments (see Private Capital Sees A Cheap Public Market). We think the market doesn’t fully appreciate the cashflow reliability inherent in many midstream businesses. This is what’s drawing in outside capital, with structures that seek to isolate this benefit without imposing any meaningfully higher risk on existing investors.
JPMorgan found that investors in Oneok were critical of a structure that used capital with an IRR of 7.25% or possibly higher to reduce debt yielding around 5%, although the reduced leverage does justify this for some.
Williams Companies (WMB) took a different approach in their partnership with Blackstone by carving out a portion of Behind The Meter (BTM) deals into a separate entity. This approach allows for a valuation of specific assets, potentially at a higher level than when embedded within the overall corporate structure. We think there will be more examples of this which should ultimately help the sector resolve to a higher valuation.
Higher crude oil prices garnered headlines last week, along with record prices for diesel. The continued move higher in global LNG prices has been just as impressive if less widely reported. The European TTF benchmark is above $26 per Million BTU compared with the US at below $3. Exploiting the vast arbitrage is available to those with spare liquefaction capacity, notably Venture Global. Their strategy of retaining some capacity for themselves is allowing them to profit more effectively from today’s opportunity than Cheniere, which has committed 95% through 2035. The two companies offer a different risk profile and exposure to LNG price differentials.
But both stand to benefit over the long run, along with NextDecade from Qatar’s protracted inability to ship LNG out of the Persian Gulf. US hydrocarbon exporters more broadly should see a boost over the long term, including Enterprise Products Partners and Targa Resources for their ability to supply LPGs.
My wife and I are in Europe, home of the world’s most dysfunctional energy policies and consequently some of the highest electricity prices. European natural gas stocks have been running below normal levels for this time of year while prices have inconveniently moved up. Replenishing those stocks in time for winter will likely require government subsidies to avoid the political damage of even higher household fuel bills.
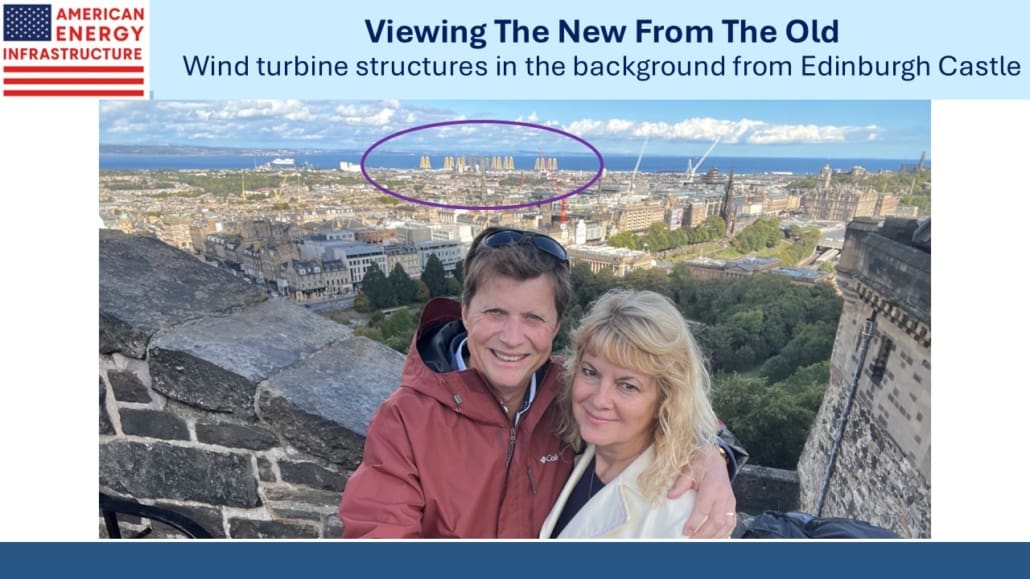
Like much of Europe, Edinburgh, where we visited last week, consumes energy more sparingly. Hotel corridors have motion sensitive lighting. The electric hand-dryers in the washrooms shut off more quickly. Windpower has been relatively successful in the UK, providing over a quarter of the country’s electricity and on some days all of it. Coal has been completely phased out.
Scotland generates more than it can use, and the infrastructure to transmit the excess south to England remains inadequate. Regional pricing doesn’t reflect local abundance, so Scots grumble about subsidizing their Sassenach neighbors with cheap windpower.
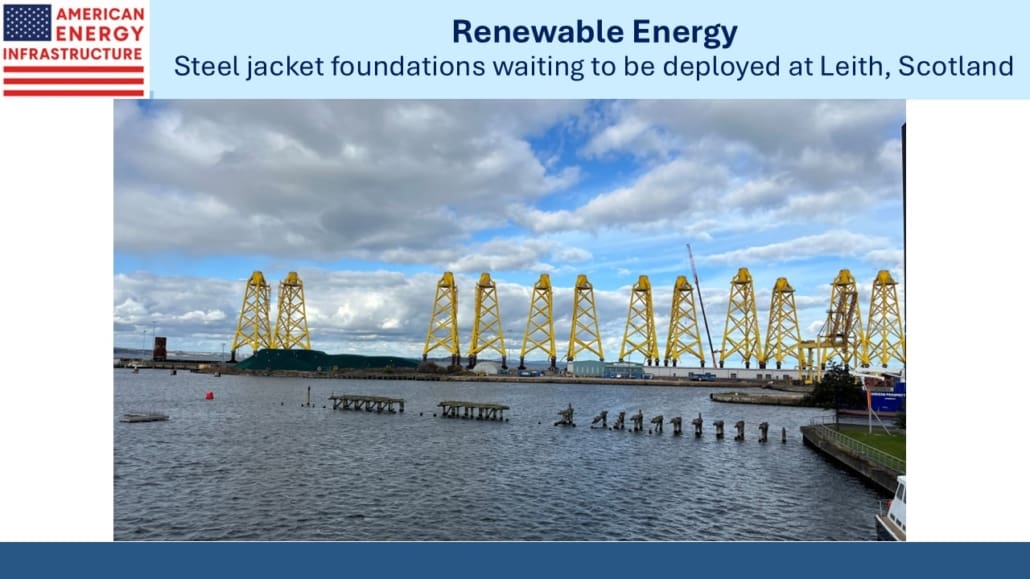
Britain’s surrounding waters are reliably windy. We saw several jacket foundations, the steel yellow lattice structures that support wind turbines, lined up on the port in Leith ready to be moved offshore. They’re built in China where coal is the dominant form of energy and shipped from the other side of the world. For decades the North Sea has provided oil and gas. Now it’s also providing electricity.
Household electricity prices in the UK are roughly double the US average, while industry pays two and a half times as much. Renewables are expensive in most of the places they’re deployed at scale around the world, although the US also benefits from cheap natural gas. Around a quarter of UK power comes from gas, but given the prices noted above it’s expensive. With coal reserves exhausted, windpower seems like a sensible option.
Thanks to the shale revolution, America remains the home of cheap energy.
We have two funds that seek to profit from this environment: